 Sector Insights
Listen to this Recap
11:54
Bond Shock and Oil Rally Drive a Tilt Toward Energy, Utilities and Industrials as Regulatory Risk Clouds Crypto and Cannabis
Podcast • Loading audio...
Share this article
Spread the word on social media
Key Takeaways
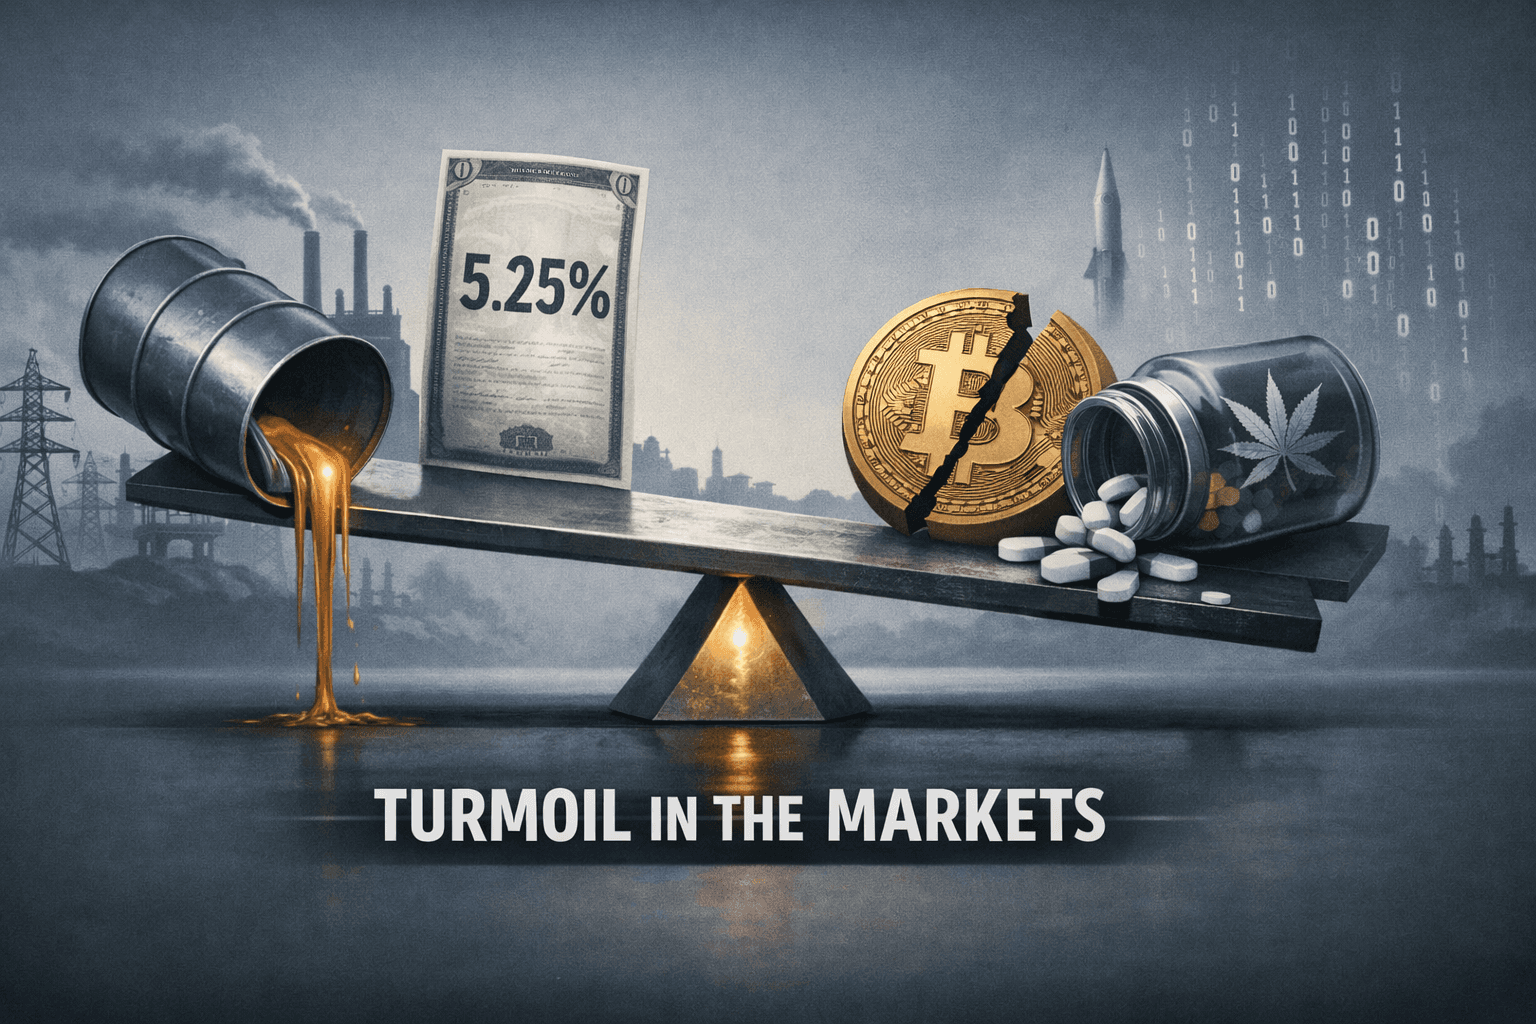
- •Treasury yields near 5.25% and Brent topping $100 set the macro backdrop — benefitting energy while pressuring rate-sensitive sectors like finance and real estate.
- •Large industrial and logistics investments (e.g., Ford–JPMorgan–Michigan $3bn, Maersk expansion) underpin industrials and materials demand despite a tighter funding environment.
- •Renewables and storage momentum (27% storage-market expansion cited) support utilities and battery-material supply chains, aided by federal grid and tax-policy moves.
- •Regulatory and security headlines — a paused DEA rescheduling, an evolving Bitget heist, and data-breach concerns — are creating idiosyncratic volatility in cannabis, crypto and select tech names.
- •Monitor yields, oil and credit spreads alongside key regulatory calendars (DEA, FERC, SEC) for signals that will likely determine sector leadership in the coming weeks.
Executive summary
Markets closed the quarter under a mixed but decidedly macro-driven tape: a bond-market repricing and a resurgent oil complex dominated cross-sector direction. Treasury yields sitting near 5.25% squeezed rate-sensitive corners of the market and tightened corporate funding conditions, while Brent crude topping $100 and supply disruptions (including a Russian diesel export ban and shifting Indian flows) lifted energy-linked sectors. Against the macro backdrop, corporate-capex and policy headlines produced winners and losers: large-scale industrial investments and renewable-grid projects underpinned industrials, utilities and materials, while regulatory uncertainty and security incidents left crypto and cannabis trading with elevated risk premiums.
Key data points that shaped the day: Treasury yields around 5.25% (reported in finance coverage), Brent crude above $100/bbl, and a 27% expansion cited for energy storage markets in renewables headlines. Large corporate moves included a $3 billion Ford–JPMorgan–Michigan initiative and several multi-billion-dollar project proposals (a proposed $15 billion steel mill). At the same time, the FBI-style headlines — a continued Bitget heist morphing into Zcash flows and a DEA judge pausing federal cannabis rescheduling — increased political and legal uncertainty for specific pockets of the market.
This report groups sectors by performance, traces cross-sector linkages, highlights the day’s most market-moving stories and sets out the indicators and events investors should watch in the coming weeks. As always, analysis is for informational purposes and not individualized investment advice.
Performance groups: outperformers, underperformers, stable
Below we group the 24 sector briefs into broad performance buckets based on the day’s headlines and implied market reaction.
Outperformers (momentum/positive news drivers)
- Energy: Oil rallied (Brent > $100) and long-term demand signals from Guyana and LNG deals drove a constructive tape for exploration, production and midstream-related exposure.
- Utilities: Renewables, storage expansion (a cited 27% storage market increase) and federal grid reforms — plus localized manufacturing builds (solar manufacturing in South Carolina) — put utilities and adjacent grid contractors into a favorable spotlight.
- Industrials: Large-scale investment announcements (Ford–JPMorgan–Michigan $3 billion initiative, Maersk U.S. logistics expansion, proposed $15 billion steel mill) and logistics/capacity builds suggested positive demand for machinery, industrial services and logistics real estate.
Underperformers (headline-driven pain points)
- Finance: A “generational” jump in bond yields compressed bank margins, pressured funding-sensitive names and tightened corporate borrowing conditions; the day’s tone was broadly negative for financials.
- Crypto: Security incidents remain front-and-center — the ongoing Bitget-related heist, regulatory scrutiny of prediction markets and liquidity concerns left crypto risk premia elevated.
- Cannabis: A paused DEA rescheduling hearing and continued federal policy uncertainty drove fresh regulatory risk for cannabis equities and related assets.
Stable / mixed (idiosyncratic winners and losers within sector)
- Materials: Deal flow, tailings JVs and recycling moves showed industry activity but geopolitics and commodity cycles kept returns uneven.
- Consumer & Retail: M&A (Hormel’s ~$1 billion chicken deal), AI catalog rollouts and price moves created differentiated outcomes across retail and branded names.
- Technology & Communications: Innovation headlines (DoorDash drones, Apple Pay India) were balanced by security incidents (military data breach) and platform disputes, producing a choppy, mixed tape.
- Real Estate: Big financings and leasing activity offset construction-cost pressure and credit-rule concerns; performance depended on balance-sheet strength and rate-sensitivity.
- Healthcare: Research advances and wearable-AI pushed some benches forward, while payer restrictions and legal suits increased uncertainty.
Note: These groupings reflect the thematic weight of the day’s headlines rather than explicit intraday price lists; absent a unified performance dataset, they indicate which sectors were likely bid or sold given the news flow.
Cross-sector themes and correlations
Several themes cut across sectors and help explain why certain groups outperformed or underperformed.
- Rates and financing cost transmission
- Treasury yields approaching 5.25% tightened funding and raised discount-rate pressure on long-duration assets. Finance and real estate are directly affected through higher funding costs and mortgage-rate sensitivity; technology and growth stocks feel the valuation effect of a higher discount rate. Banks faced compressed spreads and balance-sheet pressures as bond-markets repriced.
- The financing backdrop also tempers near-term M&A and capex math for highly levered projects, even as large corporates with strong credit profiles continue to invest (see Ford and Maersk investments).
- Energy supply shocks lift commodity- and capital-intensive sectors
- Brent > $100, a Russian diesel export ban, and shifting import patterns from India tightened markets and fed through to higher near-term revenues for energy producers and midstream. That ripple lifts materials (cement, steel) in regions exposed to higher input costs, and benefits some industrial names with energy-linked pricing power.
- Renewables and electrification remain policy- and capex-driven
- Grid reform, federal tax credits and local manufacturing expansions (solar in South Carolina) supported utilities and battery/storage installers. The reported 27% storage market expansion points to multi-year service and equipment demand that benefits utilities, industrials and certain materials (battery metals, recycling).
- Regulatory and security risk increases idiosyncratic volatility
- Crypto (Bitget heist moving to Zcash) and cannabis (DEA rescheduling pause) show how legal and enforcement uncertainty can produce outsized swings for niche sectors. Healthcare likewise faces policy and legal headwinds — from Medicaid eligibility changes to biotech suits — that can cause uneven returns irrespective of underlying innovation.
- Corporate operational shifts and AI are reshaping consumer and tech narratives
- Companies are investing in AI cataloging, platform tweaks (Amazon ads) and logistics automation (DoorDash drones) to reduce cost and reaccelerate growth—offsetting some pressure from rates and input inflation.
Most significant moves today and why they mattered
A short list of the day’s highest-impact items, with context on why the market took notice.
Treasury yields near 5.25% — a macro fulcrum
- Why it mattered: Higher yields reverberate across equity sectors by raising discount rates and increasing borrowing costs for corporate America. The finance sector signaled acute pressure as banks faced bond-mark portfolio markdowns and funding-cost jumps. For real estate and other rate-sensitive sectors, higher financing costs can slow transactions and capex.
- Market implications: Short-term risk-off pressure and narrower appetite for long-duration tech names; increased attention to bank balance sheets and credit spreads.
Brent crude topping $100/bbl and oil-side supply moves
- Why it mattered: Russia’s diesel export ban and India’s shifting import flows tightened global fuel balances, pushing Brent above $100. Energy producers benefit directly through higher realizations; refiners and logistics providers see margin and throughput effects, and materials tied to energy-intensive industries (cement, steel) face cost pressures.
- Market implications: Energy and certain industrials outperform; inflation signals may influence Fed and fiscal policymaking discussions.
Ford–JPMorgan–Michigan $3 billion initiative and industrial capex
- Why it mattered: Large, targeted public–private investment signals continued corporate willingness to fund industrial capacity and EV-related infrastructure. These moves translate into multi-year revenue streams for manufacturers, logistics providers and construction-service firms.
- Market implications: Positive for industrials, equipment makers and materials suppliers; the sector’s performance increasingly driven by real economy capex rather than pure sentiment.
Utilities and storage wins: 27% market expansion
- Why it mattered: Solar manufacturing in South Carolina, calls for grid reform (FERC on PJM delays) and a cited 27% growth in the storage market anchor a constructive narrative for utilities and clean-energy supply chains.
- Market implications: Favorable for utilities with regulated returns, storage installers, and battery-material suppliers.
Crypto security incident evolves: Bitget heist to Zcash
- Why it mattered: The continuing flow of stolen assets into privacy-preserving coins (Zcash) complicates recovery and heightens regulatory scrutiny; coupled with regulators targeting prediction markets, the sector faces both operational and legal headwinds.
- Market implications: Heightened volatility, renewed focus on custodial and AML practices, and potentially increased regulatory actions that could reshape product availability.
DEA rescheduling pause for cannabis
- Why it mattered: Federal rescheduling would have been a major structural change for the industry; a judicial pause perpetuates state-by-state fragmentation and keeps federal banking, tax and capital-access issues unresolved.
- Market implications: Continued discounting of cannabis equities and continued reliance on local/vertical-operational momentum rather than national capital-market arbitrage.
Security and platform friction in tech and communications
- Why it mattered: A major military data breach, OpenAI-related disputes, and platform access fights (Reddit) elevate governance and security as investment considerations. At the same time, product launches (Apple Pay India, DoorDash drones) show ongoing revenue-creation vectors.
- Market implications: Mixed; security issues can depress multiples for impacted firms while new product rollouts offer positive fundamental drivers for others.
Actionable insights and indicators for investors (informational, non-personalized)
Below are monitorable signals and management actions that analysts and market-watchers may find useful in the coming weeks.
Macro and market indicators to watch
- Treasury yields and the 10-year/2-year curve: follow moves off the 5.25% level and changes in the slope for funding-cost implications.
- Oil benchmarks (Brent, WTI) and diesel inventories: sustained levels above $100 materially alter sector revenue outlooks and inflation expectations.
- Credit spreads and bank funding indicators: widening spreads signal pressure on lending and potential slowdown in lending-driven sectors.
- Storage capacity and project awards: track announced offtake and storage pipeline to gauge clean-energy capex velocity.
Sector-specific signals
- Finance: watch bank balance-sheet disclosures for mark-to-market losses, deposit outflows, and the pace of new originations; monitor Fed and regulatory commentary on stress-test changes.
- Energy: track rig counts, high-frequency shipping and storage data, and major upstream project timings (Guyana production ramp toward 1m bpd was cited).
- Utilities & grid: follow FERC rulings, PJM scheduling changes, and local manufacturing investment announcements; tax-credit guidance is important for project-level economics.
- Industrials & materials: monitor announced capex and supply-chain bottlenecks (e.g., steel mill proposals), plus recycling and circular-economy deals that shift raw-material demand profiles.
- Crypto & cannabis: keep an eye on regulatory docket items (DEA schedule rulings, SEC actions, exchange regulatory updates) and forensics on any major security incidents.
Practical portfolio considerations (informational)
- Reassess duration exposure: Given the higher rate environment, revisit duration sensitivity within equity valuations and fixed-income portfolios.
- Stress-test funding-dependent cash flows: For real-estate, financials and leveraged corporates, simulate higher-rate scenarios and slower refinancing timelines.
- Follow policy calendars: Regulatory decisions (DEA, FERC, SEC) can produce outsized, rapid repricings in targeted sectors; make sure relevant dates are on the watchlist.
- Watch liquidity and margin: Higher volatility and headline risk can narrow market liquidity — be alert to execution risk and wider bid-ask spreads in niche securities (small caps, crypto tokens).
Sector-by-sector snapshot (high-level takeaways)
A concise note on each sector based on today’s news flow.
- Energy: Rally on supply-side constraints and demand signals (Brent > $100; Guyana production growth; multi-decade LNG deals). Positive top-line implications for E&P and midstream names.
- Utilities: Renewables push ahead with storage tailwinds (27% growth cited), SC solar manufacturing plans and FERC grid reform commentary.
- Industrials: Heavy investment activity (Ford–JPMorgan–Michigan $3bn; Maersk US logistics; proposed $15bn steel mill) supports equipment makers and logistics.
- Materials & Mining: Active deal-making (copper tailings JV, $133.65m raise for U.S. iron for rare-earth magnets), recycling deals improving supply dynamics.
- Finance: Bond rout, Treasury yield spike (~5.25%) compresses bank margins; mixed offsets from stress-test tweaks and regional consolidation headlines.
- Real Estate: Financing and leasing activity balanced by construction-cost pressures and mortgage-rate sensitivity; policy and credit-rule updates (VantageScore 4.0 acceptance by Fannie/Freddie) are notable.
- Technology: Product and platform innovation juxtaposed with security and governance friction (military data breach, platform disputes); Apple Pay India and AI hardware pushes remain growth vectors.
- Communications & Media: Content wins offset talent exits and satellite launch concerns; mix of global deals and legacy-media headwinds.
- Consumer & Retail: AI in merchandising and ad-platform changes (Amazon) coexist with M&A (Hormel $1bn chicken deal) and price competition (Target cuts) affecting margins.
- Healthcare: Scientific advances and wearable AI balanced against policy/legal risks and payer-driven access constraints.
- Crypto: Continued security incidents (Bitget heist) and regulatory scrutiny cause elevated volatility; on-ramp product innovations coexist with operational risks.
- Cannabis: Federal rescheduling delay renews uncertainty; state-level policy progress keeps operational momentum but capital-access remains constrained.
Other sectors (communications, specialized industry sub-areas, etc.) had mixed, idiosyncratic moves tied to local deals, talent shifts and product launches; these will matter more at the stock-level than for broad sector beta in the near term.
Conclusion and forward-looking perspective
As the quarter closes, the market’s storyline is bifurcated: macro forces (higher yields and an oil rally) set a heavier cross-asset tone, while targeted, idiosyncratic developments (major industrial capex, grid and storage expansions, and discrete regulatory moves) create pockets of opportunity and risk. The path of Treasury yields and oil prices will likely remain the dominant macro levers in the coming weeks, shaping sector leadership and risk appetite.
Regulatory calendars (DEA scheduling, FERC rulings, SEC/crypto oversight) and ongoing security incidents represent asymmetric, headline-driven risks that can quickly reprice niche sectors. On the constructive side, sustained industrial investment and accelerating renewable/storage deployments suggest durable demand for equipment, logistics and materials — a potential multi-quarter tailwind for industrials, utilities and related suppliers.
Investors should monitor yields, oil benchmarks, credit spreads and key regulatory dates while watching corporate balance sheets for resilience to higher funding costs. Market volatility into the new quarter is likely, and sector leadership will depend on the interplay between policy outcomes, commodity cycles and the evolving rate environment.
Investment disclaimer: This report presents market analysis and sector-level observations for informational purposes only. It does not constitute personalized investment advice, and it does not recommend buying, selling or holding any specific security.
Sources
+ 14 more sources
Use these insights — enter this week's contest.
Free practice contests — earn Alpha CoinsExplore More Content
Disclaimer: StockAlpha.ai content is for informational and educational purposes only. It is not personalized investment advice. Sentiment ratings and market analysis reflect data-driven observations, not buy, sell, or hold recommendations. Always consult a qualified financial advisor before making investment decisions. Past performance does not guarantee future results.
Spotted something wrong? Report an error.