 Sector Insights
Listen to this Recap
12:14
Capex, AI and Energy Friction Drive Sector Rotation — Industrial & Materials Lead; Energy, Healthcare, Cannabis Lag
Podcast • Loading audio...
Share this article
Spread the word on social media
Key Takeaways
- •Capex and project milestones (steel, mines, solar, hydrogen) powered industrials and materials today.
- •AI fundraising and market‑plumbing wins (OpenAI funding reports; Coinbase DCO approval) underpin technology and crypto structural narratives but raise governance questions.
- •Energy faced a tug‑of‑war between SPR releases and geopolitical supply risk, producing uneven sector performance.
- •Regulatory and legal developments remain the dominant cross‑sector risk — monitor court dockets and policy calendars closely.
Executive summary
Markets today were shaped less by a single macro data print than by a string of sector-specific, high‑impact headlines. Corporates and governments continued to deploy big capital: proposed greenfield factories, steel mills and logistics hubs dominated industrial and materials coverage, while real‑estate deals and refinancing pointed to pockets of leasing strength. Technology headlines were dominated by AI dealmaking and governance noise — most notably a reported $30 billion pre‑IPO raise for OpenAI at a ~$1.4 trillion implied valuation — that kept investor attention on long‑term monetization rather than near‑term revenue surprises.
At the same time, energy markets showed cracks: supply risks from the Middle East prompted emergency headlines even as an additional 40 million barrels from the U.S. Strategic Petroleum Reserve was announced. Healthcare and cannabis were pressured by legal and policy uncertainty despite sizable transactions (a $2.6 billion obesity-drug deal in healthcare). Crypto showed infrastructure progress (Coinbase securing DCO approval) even as on‑chain metrics signaled profit‑taking.
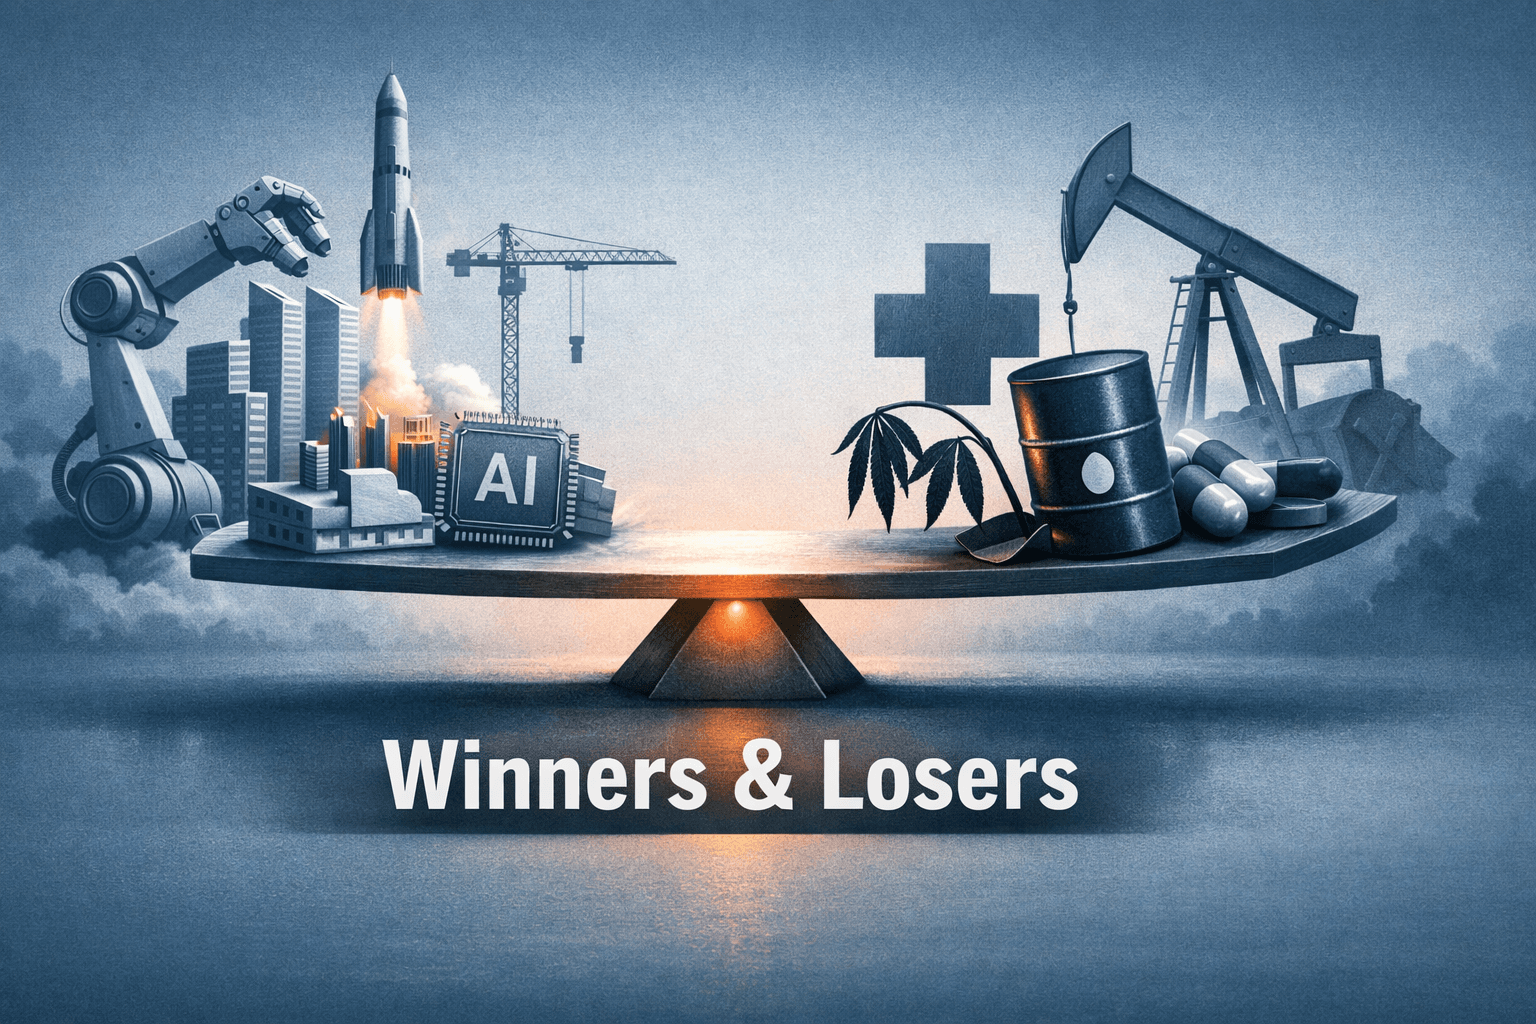
Net-net, the tape favored capital‑intensive, cyclical and infrastructure‑linked sectors (industrial, materials, real estate) while sectors more sensitive to policy, legal outcomes and demand softness (energy, healthcare, cannabis) underperformed or produced mixed signals. Technology and utilities printed mixed results as AI bullishness competed with regulatory and operational risk.
Grouping by performance: outperformers, underperformers, stable
Note: performance groupings below are derived from the balance of today's headlines and capital flows rather than intraday price moves.
Outperformers
- Industrial & Manufacturing: Multiple large capital projects set the tone — a proposed $15 billion steel mill, a $500 million distribution center and accelerating investments in precision manufacturing and defense supply chains. These headlines suggest near‑term visibility into capacity builds and longer‑term revenue streams.
- Materials & Mining: Financing and project milestones underpinned the sector. Troilus secured an $850 million credit package and Fortescue marked first hot‑metal output — a combination of capital availability and production progress that supports commodity cycles and metals prices.
- Real Estate: High‑visibility leases and financings drove select strength — examples include a 60‑year Brooklyn campus lease and a $66.5 million Union Square refinance — signaling demand pockets in life‑science and long‑term office uses despite broader renovation softness.
Underperformers
- Energy: Mixed signals — geopolitical supply risk (Iran) pushed price sensitivity higher, but a 40 million barrel SPR release, weakening LNG flows and project pauses in some regions muted a clear rally. Policy and demand worries left the sector uneven.
- Healthcare: Scientific advances and big M&A‑sized deals coexist with legal and policy uncertainty. A $2.6 billion obesity deal was balanced by Medicare/Medicaid policy moves and court attention to pricing and access.
- Cannabis: Labor disputes, stalled legalization headlines and state‑level legal fights (Ohio, Missouri) kept the sector under a cloud despite incremental medical and hemp research upside.
Stable / mixed
- Technology: Large private financing for OpenAI ($30B pre‑IPO at an implied $1.4T valuation) and Anthropic’s IPO filing (with disclosure of heavy losses) kept investor focus on AI runway, fundraising dynamics and regulatory scrutiny rather than uniform share‑price direction.
- Utilities: Project progress (715 MW solar, green hydrogen operations at DeBary, a 20‑MW Bronx battery) balanced operational and workforce strain concerns, leaving the sector in a cautiously constructive but watchful posture.
- Communications & Media: Studio release calendars and infrastructure investments (antenna/5G competing product stacks) create near‑term content catalysts but longer‑term consolidation and cost dynamics temper enthusiasm.
- Crypto: Infrastructure improvements (Coinbase DCO approval) and macro tailwinds (Bitcoin posting its third monthly gain) were offset by on‑chain profit‑taking flags.
Cross‑sector themes and correlations
- Capital intensity and the capex rotation
- Heavy capex headlines — steel plants, EV‑centric battery projects, distribution centers and mine financing — showed a coordinated move into physical capacity. Materials and industrial names are benefiting in tandem: mines need offtake for steel projects; logistics facilities support retail and manufacturing growth. The capital cycle correlation suggests coordinated earnings momentum for cyclical supply‑chain beneficiaries over the next 6–18 months.
- AI and software as cross‑sector accelerant and governance risk
- AI headlines cut across technology, communications, consumer and finance. OpenAI’s reported $30 billion pre‑IPO round and Anthropic’s IPO filing highlighted investor appetite but also raised questions about governance, losses and regulatory scrutiny (AI safety warnings). Media companies pushing AI for recommendation and production systems could extract value, but broadcasters and platform incumbents face consolidation pressure and regulation that could alter competitive dynamics.
- Energy transition friction: overlap between utilities, energy and materials
- Green hydrogen start‑ups (DeBary facility), large solar arrays (715 MW deal) and battery deployments (20 MW Bronx project) illustrate the energy transition in practice, but supply chain needs (lithium, nickel) connect materials/mining to the utilities and EV ecosystem. Conversely, policy headwinds and geopolitical energy supply shocks (Iran tensions, SPR releases) can dampen investor enthusiasm and create volatility across commodity and renewable investment cases.
- Regulatory and legal risk as a unifying dampener
- Healthcare reimbursement, cannabis licensing fights, EU DMA and AI regulatory pushes, and information‑security flags in finance all highlighted regulatory risk as a market‑wide theme. These risks compress certainty and can widen equity risk premia for affected sub‑sectors.
- Infrastructure and market plumbing upgrades supporting new asset classes
- Crypto clearing and custody developments (Coinbase DCO approval) and exchanges/clearinghouse moves suggest maturation of market infrastructure that could support next‑stage institutional flows into digital assets, but on‑chain indicators show profit‑taking risk remains.
Notable single‑day moves and why they matter
OpenAI reported pre‑IPO effort (~$30B at a ~$1.4T implied valuation)
- Why it matters: This is a capitalization and valuation signal for the AI ecosystem. A large, private fundraise at a trillion‑plus valuation calibrates expectations for AI monetization and funds long‑term R&D and go‑to‑market scaling. It also raises governance and dilution questions for future public investors and amplifies regulatory scrutiny on dominant model providers.
Coinbase gets DCO approval; Bitcoin posts third monthly gain
- Why it matters: Institutional market plumbing improved materially with Coinbase’s clearing capabilities. DCO approval reduces counterparty and settlement friction for U.S. institutional participation, potentially deepening liquidity. Bitcoin’s third monthly gain in a row signals continuing macro and flows support, but on‑chain metrics today flagged profit‑taking — underlining short‑term volatility risk even amid structural interest.
Large industrial and materials capex (proposed $15B steel mill; Troilus $850M credit; Fortescue hot metal)
- Why it matters: These announcements translate into multi‑year demand for iron ore, coking coal and downstream fabrication. Advances in mining financing plus early production from major miners increase supply visibility and reduce project execution risk. For investors, capex creates a pipeline of revenues for equipment vendors, logistics and service providers.
Energy headlines: 40 million barrels SPR release vs. Iran supply risk
- Why it matters: The SPR release is designed to blunt price spikes from geopolitical shocks, but it is a short‑term liquidity tool. Structural demand weakness in LNG flows and project pauses make the energy outlook fragile: policy moves can mute rallies even while headline risk remains elevated.
Healthcare: $2.6B obesity deal amid policy/legal noise
- Why it matters: Big transactions show M&A appetite and value creation in drug markets (particularly obesity therapeutics), but the sector’s sensitivity to reimbursement policy and litigation could compress valuations if pricing interventions gain momentum.
Utilities and renewables pipeline (715 MW solar, DeBary green hydrogen, 20 MW battery)
- Why it matters: Concrete project starts on hydrogen, storage, and large‑scale solar illustrate where CapEx is being deployed to meet net‑zero commitments. These projects support multi‑year cash flows for developers and create demand pull for advanced materials and grid equipment.
Real estate: 60‑year Brooklyn campus lease; $66.5M Union Square refinance
- Why it matters: Long‑term, large leases in gateway markets signal tenant willingness to commit, supporting REITs and property owners in niche subsectors (life sciences, long‑duration office uses). Refinancings at scale point to improved access to capital for select assets.
Cannabis: Legal battles and labor conflict
- Why it matters: State‑level legal rulings and workforce disputes keep operating risk high and slow rollouts, suppressing valuation multiple expansion despite underlying demand trends in medical markets.
What this means for investors — actionable insights (informational only)
- Favor visibility into multi‑year contractual cash flows
- The wave of large capex projects creates predictable revenue opportunities for equipment suppliers, logistics providers, contract manufacturers and niche service companies. Analysts note that firms with long‑dated offtake agreements or backlog tied to industrial builds may offer more predictable earnings as construction ramps.
- Watch regulatory calendars and court dockets
- Policy headlines drove today’s dispersion. Monitor upcoming legislative windows and major court dates (AI/tech regulatory actions in the EU, Medicare/Medicaid deliberations, state cannabis rulings). Regulatory outcomes can rapidly re‑rate affected sectors.
- Distinguish transient headline risk from structural demand
- In energy, the SPR release is a temporary dampener; however, underlying LNG flows, project sanctions and demand trends are the structural drivers. Investors and analysts should separate short‑term price‑ameliorating moves from lasting shifts in supply/demand balances.
- Use infrastructure improvements as a signal, not a green light
- Coinbase’s DCO approval and other market‑plumbing upgrades lower operational barriers for institutions. That increases the probability of more flows into digital assets, but liquidity and on‑chain indicators still point to episodic volatility. Position sizing and risk controls remain important.
- Monitor financing terms and project execution risk
- Troilus’s $850 million credit package and other financing headlines are positive early signals, but project delays or cost overruns (common in large mining and energy projects) can blow out returns. Analysts will watch capex-to-completion timelines and supplier contracts closely.
- Focus on companies with flexible cost structures and pricing power in consumer and retail
- Retailers that showed operational strength (Costco, Puma references) competed against those cutting prices (Target) — a reminder that margin trends will continue to diverge across the sector. Firms that can flex pricing or extract productivity from AI and logistics upgrades may outperform in a soft demand environment.
Key short‑term data points to watch next
- Regulatory milestones: EU DMA cases, major state‑level cannabis court rulings, Medicare/Medicaid policy announcements.
- Energy flow statistics: weekly SPR data, LNG shipment volumes and OPEC/Iran headlines.
- Corporate reporting on capex and backlog: updates from major miners, steelmakers, and key industrial suppliers on timelines and cost inflation.
- AI governance and funding: fundraising rounds for major private AI players, IPO filings and associated disclosure about losses and regulatory risk.
- Crypto market microstructure: on‑chain flows, institutional custody and clearing adoption metrics following DCO approvals.
Risks and counter‑arguments
- Policy shock risk: The same legal and regulatory frameworks that protect consumers can rapidly compress valuations and create stop‑orders on projects (seen in cannabis and parts of healthcare).
- Execution risk: Big capital projects bring higher odds of cost overruns, permitting delays and supply‑chain bottlenecks. Financing availability today does not remove execution risk.
- Valuation sensitivity: Some technology and AI valuations are being set in private transactions rather than public markets, which could create re‑rating risk when public windows open.
- Macro overlay: A macro surprise (rate shock, recession signal) would re‑weight investor preference for low‑beta, dividend‑paying utilities and stable consumer names and could reverse the capex trade quickly.
Conclusion and forward look
Today’s tape reinforced a bifurcated market narrative: heavy capital deployment and infrastructure upgrades are supporting industrial, materials and select real‑estate plays, while legal, policy and demand uncertainty keeps pressure on energy, healthcare and cannabis. Technology remains a heavyweight, with AI‑driven capital and regulatory oversight both escalating.
Over the coming weeks, investors should watch regulatory calendars and execution markers for large projects as primary re‑rating drivers. If capex projects keep progressing on budget and AI funding continues to flow, the cyclical recovery story anchored in industrials and materials could gain momentum. Conversely, adverse regulatory outcomes in healthcare or tighter political responses to AI and crypto could re‑introduce cross‑sector volatility.
Investment disclaimer: This article is for informational purposes only. It does not constitute investment advice, an offer to buy or sell securities, or a personal recommendation. Analysts note trends and data that market participants may consider; readers should consult a qualified financial advisor before making investment decisions.
Key takeaways
- Capital intensity dominated: large industrial and materials projects (e.g., proposed $15B steel mill, Troilus $850M credit) are driving today’s leadership.
- AI and market plumbing developments (OpenAI reported $30B round; Coinbase DCO approval) are structural catalysts but bring governance and volatility risks.
- Energy and policy‑sensitive sectors lagged as SPR releases and geopolitical supply risk created mixed signals.
- Regulatory and legal headlines (healthcare reimbursement, cannabis licensing, EU tech rules) are principal near‑term risk factors.
- Investors should prioritize earnings visibility, execution metrics and regulatory calendars when assessing sector exposure.
Sectors to watch for next session
- Industrial & Materials: follow capex updates and mine output guidance.
- Technology & Communications: monitor AI filings, DMA cases and content release calendars.
- Energy & Utilities: watch SPR flows, LNG shipments and permitting updates for renewable projects.
Sources
+ 14 more sources
Use these insights — enter this week's contest.
Free practice contests — earn Alpha CoinsExplore More Content
Disclaimer: StockAlpha.ai content is for informational and educational purposes only. It is not personalized investment advice. Sentiment ratings and market analysis reflect data-driven observations, not buy, sell, or hold recommendations. Always consult a qualified financial advisor before making investment decisions. Past performance does not guarantee future results.
Spotted something wrong? Report an error.