 Market Recap
Listen to this Recap
10:54
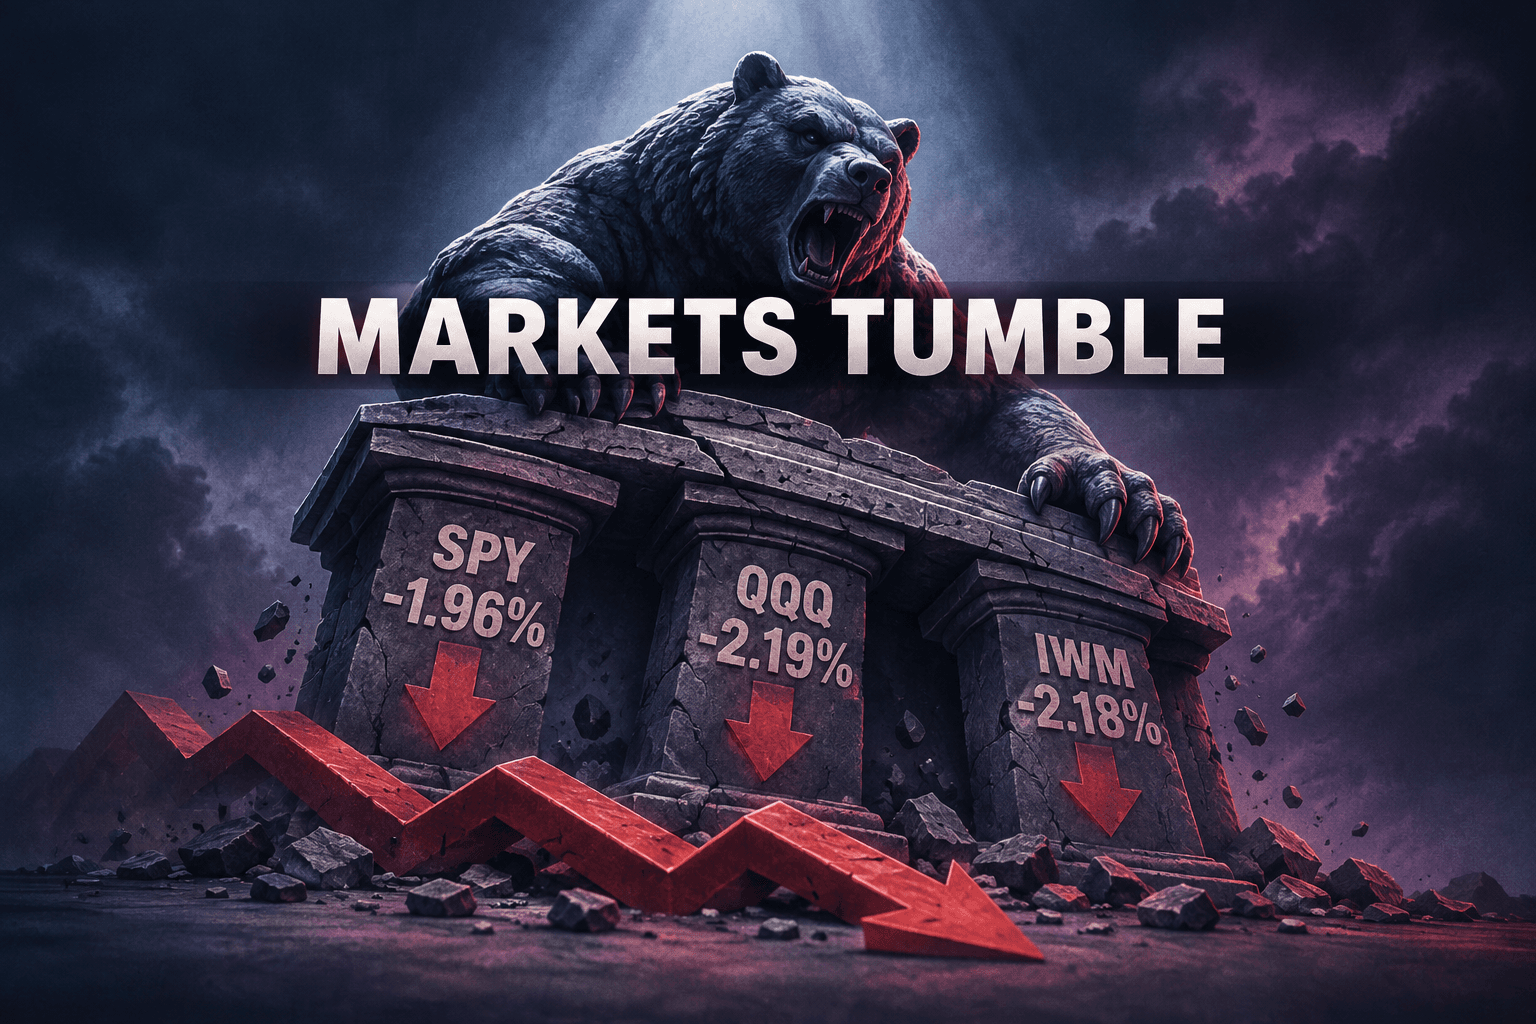
Broad Risk-Off Session Hits Stocks: SPY Falls 1.96%, QQQ and IWM Drop More Than 2%
Podcast • Loading audio...
Share this article
Spread the word on social media
Key Takeaways
- •SPY fell 1.96%, QQQ declined 2.19%, and IWM lost 2.18% in a broad risk-off session.
- •The close performance of the three ETFs indicates weakness across large-cap, technology-heavy and small-cap segments.
- •Palo Alto Networks was reported to have jumped after an earnings beat, but no exact move or complete stock leaderboard was supplied.
- •Headlines highlighted crypto weakness, rate-sensitive real estate and mixed signals in commodities, consumer businesses and industrials; sector returns were not provided.
- •No specific economic release, Fed announcement or Treasury-yield move was included, limiting conclusions about the macro catalyst.
A broad decline sets the tone
U.S. stocks had a decisive risk-off session on Nov. 19. The S&P 500 ETF (SPY) fell 1.96%, the Nasdaq-100 ETF (QQQ) lost 2.19%, and the Russell 2000 ETF (IWM) declined 2.18%. The drops were close in scale, showing that weakness was not confined to technology megacaps: smaller companies also came under substantial pressure. QQQ’s slightly larger decline left the technology-heavy index proxy at the bottom of the three, but the gap was modest.
The market’s broad retreat stands out against a news agenda that was busy but mixed. Coverage ranged from crypto weakness and gold’s extended downturn to industrial activity, grid investment, media rules, real-estate transactions and company-specific earnings. Those headlines help describe the day’s competing themes, but the supplied data does not establish which one drove the index selloff. Nor does it include trading volume, Treasury yields, market breadth or individual closing prices that would support a more detailed attribution.
The clearest takeaway is therefore the breadth and magnitude of the decline, rather than a confirmed single-catalyst story. All three major ETF proxies fell close to 2%, suggesting a generally cautious session across large-cap growth, the broader S&P 500 and small caps. The small-cap decline was nearly in line with QQQ’s, a reminder that the day’s weakness extended beyond the largest technology names.
Sector rotation: a complicated backdrop, not a confirmed leaderboard
The day’s sector headlines pointed in different directions. Utilities coverage focused on grid rules and rising data demand, while industrial and manufacturing stories described momentum in areas connected with building and production. Those themes may matter for longer-term company prospects, but no sector-return figures were provided. It is not possible to say from the available information whether utilities or industrials outperformed the market on Nov. 19, or whether either served as a defensive haven.
Energy coverage weighed supply and security risks, a combination that can have implications for commodity prices, operating costs and inflation expectations. Materials and mining signals were described as mixed, while a separate headline noted that gold was having a difficult year as prices continued to fall. These reports suggest uncertainty across commodity-linked businesses rather than a clear, uniform move in the materials complex. Without price data for energy, metals or related funds, the day’s market reaction cannot be quantified.
Real estate headlines centered on transactions and interest-rate risks. That focus reflects a familiar sensitivity: financing costs and the outlook for rates can influence property valuations, deal activity and the economics of development. But the supplied feed does not include mortgage rates, Treasury yields, real-estate index performance or details of the transactions. The headline is useful context, not evidence that real estate was a leading decliner or outperformer in the session.
Consumer and retail signals were also mixed. Walmart appeared in analyst commentary following earnings, and Home Depot was featured in a dividend-related item, but no stock-price reactions or earnings figures were included. The distinction matters: company coverage can be important to a sector narrative without indicating the direction or scale of that company’s trading on a given day. No ranking of consumer-sector winners or losers can be established from these headlines alone.
Crypto and commodities add to the risk discussion
The crypto sector was described as sliding as Bitcoin broke below $62,000. That is the most explicit market-price threshold in the supplied event list and adds to the day’s risk-sensitive tone. Crypto assets can respond sharply to changes in liquidity expectations, positioning and investor appetite for volatility. Still, there is no percentage move for Bitcoin or for crypto-related stocks here, and the breach alone does not establish that crypto weakness caused the equity decline.
Gold’s reported weakness offers a contrasting signal. Gold is often discussed as a defensive asset, but it does not rise in every session when equities fall. Its performance can also reflect real interest rates, currency moves and investor positioning. The headline points to a longer-running difficult period for the metal, but no Nov. 19 price change or explanation of the day’s move was supplied. It would be premature to infer a direct relationship between gold and the stock-market selloff from these items.
Company headlines: Palo Alto stands out
Palo Alto Networks (PANW) was the clearest individual-company positive in the event list, with a headline reporting that the stock jumped after an earnings beat. The report signals a favorable response to company results, but the exact earnings details and percentage move were not provided. It is therefore not possible to compare PANW’s advance with the day’s largest gainers or determine how much it offset weakness elsewhere in technology and cybersecurity.
Other company coverage was more analytical than price-focused. UnitedHealth Group (UNH) was discussed in a valuation context, Walmart drew post-earnings analyst commentary, and Alibaba Cloud’s profitability was described alongside losses at its AI labs. The Alibaba-related headlines appeared in several forms, emphasizing the tension between cloud profits and investment in AI research. That contrast reflects a broader issue for technology companies: spending on AI infrastructure and development may support future growth, while also weighing on near-term costs and margins. The available items provide no specific estimates or stock reactions, so the discussion should not be mistaken for a quantified earnings assessment.
TransDigm Group (TDG) received a Q3 update, and Applied Materials was covered for its long-term outlook. Neither item included enough information to characterize the results, guidance or share-price response. Meanwhile, communications and media coverage referenced the expected attention around GTA 6 alongside FCC rules. The headline underscores how entertainment releases and regulation can shape company-specific narratives, but it does not identify a confirmed market-moving development or a measurable impact on media stocks.
Several other headlines addressed cannabis policy and testing risks, finance and banking deal signals, and the Home Depot dividend. These are potentially consequential topics for the companies involved, but the supplied feed does not contain transaction terms, policy changes, dividend amounts or share moves. Accordingly, no individual-stock leaderboard is available. PANW is notable because the event list explicitly reports a positive earnings reaction; it cannot be labeled the session’s top gainer on the information provided.
Economic data and the Federal Reserve
No specific economic release, inflation reading, employment report, Federal Reserve announcement or Treasury-yield move was included in the market data. That limits what can responsibly be said about the macroeconomic explanation for the selloff. Rate expectations are relevant to several of the day’s topics—notably real estate, utilities, industrial investment and technology valuations—but relevance is not proof that rates changed or drove trading on Nov. 19.
For the same reason, the session should not be framed as a confirmed repricing of the Fed’s policy path. A reliable assessment would require the day’s economic calendar and results, rate-market moves, and any statements from policymakers. In their absence, the most defensible conclusion is that equities sold off broadly while the event flow highlighted a range of risks and company-specific developments. The index declines alone cannot identify whether the market was responding to growth concerns, inflation fears, valuation pressure, positioning or another catalyst.
What to watch next session
The next session’s focus will be whether the selling broadens, stabilizes or reverses. SPY, QQQ and IWM provide a useful cross-section: the first tracks large-cap U.S. equities, the second emphasizes Nasdaq-100 companies, and the third represents smaller companies. Because all three fell by roughly 2% on Nov. 19, follow-through across these proxies may help clarify whether the move was a one-session reset or part of a more persistent deterioration in risk appetite. The data supplied here does not include technical levels or closing prices, so specific support and resistance points cannot be identified.
Investors and analysts will also be watching for fresh macroeconomic information and changes in Treasury yields to better assess the rate outlook. Developments affecting Bitcoin and other risk-sensitive assets could offer additional context, while company-specific earnings and guidance may continue to create sharp divergences beneath the index level. Utilities, industrials, real estate, energy and consumer companies each have distinct exposure to rates, investment cycles and demand; their performance will need to be evaluated using actual sector data rather than headlines alone.
For now, the session’s verdict is unambiguous but its cause is not: all three major ETF proxies dropped sharply, with QQQ down the most and IWM close behind. Palo Alto Networks was highlighted as an earnings-related bright spot, but the broader list of stories was mixed and no complete stock or sector ranking was provided. The next day’s price action and any new economic or policy information will be important in determining whether Nov. 19 marks a temporary bout of volatility or the start of a more sustained market pullback. This recap is informational and does not constitute investment advice.
Sources
+ 10 more sources
Use these insights — enter this week's contest.
Free practice contests — earn Alpha CoinsExplore More Content
Disclaimer: StockAlpha.ai content is for informational and educational purposes only. It is not personalized investment advice. Sentiment ratings and market analysis reflect data-driven observations, not buy, sell, or hold recommendations. Always consult a qualified financial advisor before making investment decisions. Past performance does not guarantee future results.
Spotted something wrong? Report an error.