 Market Recap
Listen to this Recap
11:22
Small Caps Lead a Broad Retreat as Treasury-Yield Concerns Keep Pressure on Risk Assets
Podcast • Loading audio...
Share this article
Spread the word on social media
Key Takeaways
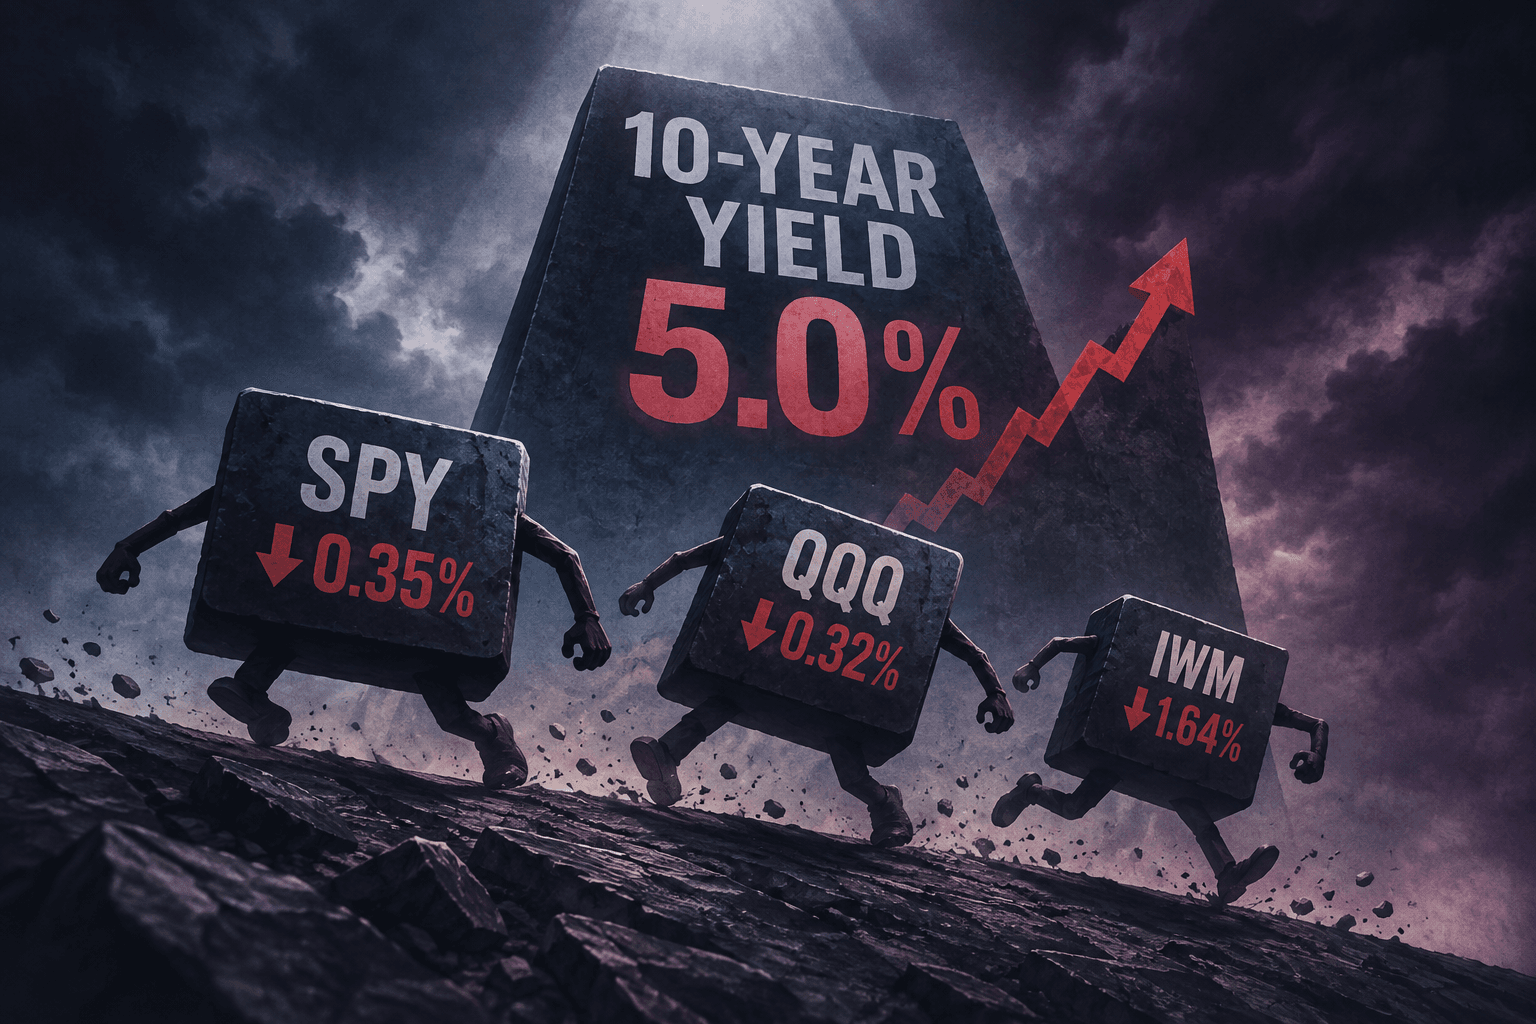
- •SPY fell 0.35% and QQQ fell 0.32%; IWM underperformed, dropping 1.64%.
- •A reported 10-year Treasury yield touch of 5% put borrowing costs and financing conditions in focus, though no closing yield or cause was provided.
- •Cerebras gained 13% after a Microsoft deal, Intel rose 7.46%, and Archer Aviation was reported up 6%.
- •Sector headlines covered utilities, materials, energy, real estate, finance and consumer businesses, but no sector-return data was supplied to confirm leaders or laggards.
- •No specific economic release or Fed announcement was included, limiting conclusions about policy expectations and the next session’s direction.
Market narrative: small caps bear the brunt
U.S. equities finished lower on November 12, with the clearest signal coming from the gap between small caps and the large-cap benchmarks. The S&P 500 ETF, SPY, declined 0.35%, while the Nasdaq-100 ETF, QQQ, slipped 0.32%. The Russell 2000 ETF, IWM, lost 1.64%—a substantially steeper drop that points to greater pressure on smaller companies than on the market’s largest stocks.
That divergence shaped the day’s story. Large-cap equities fell, but their losses were comparatively contained; smaller-cap shares had a more difficult session. The event roundup flagged a 10-year Treasury yield touch of 5%, placing interest rates and financing conditions at the center of the market discussion. The supplied data does not include the yield’s closing level, a detailed intraday timeline, or a direct attribution of the index declines to that move. Still, the combination of a high-yield headline and pronounced small-cap underperformance is consistent with a market attentive to borrowing costs and the durability of risk appetite.
The session was not uniformly negative across individual companies. News items cited sizable gains for Cerebras, Intel and Archer Aviation, even as the broad indexes fell. Those moves suggest that company-specific developments remained capable of driving outsized trading, but the available information does not include a full list of advancing or declining stocks, market breadth, or the largest index contributors.
Rates and the small-cap divide
The reported touch of 5% by the 10-year Treasury yield was the day’s most consequential macro-related headline in the supplied event list. The 10-year yield helps shape borrowing costs across the economy and is closely watched as a reference point for valuing future corporate earnings. When yields rise, the present value of profits expected further in the future can come under pressure, while debt financing may become more expensive. These effects can matter especially for companies that rely on external financing or have less flexibility to absorb higher interest expense.
That framework offers context for IWM’s 1.64% decline, but it does not establish a single cause. Small-cap performance can also reflect company-level earnings, sector composition, liquidity, and changing expectations for growth. Without intraday price data or a breakdown by industry, it would be premature to attribute the entire gap to Treasury yields. The contrast is nonetheless notable: IWM fell by more than four times SPY’s percentage loss, while QQQ tracked relatively close to the broad-market ETF.
The event feed also referred to bond-market risks beyond an AI-related market fallout. That points to a wider discussion of rates and market concentration, rather than a purely technology-focused session. No details were supplied on the specific bond-market risks or on changes in credit spreads, so the day’s available evidence supports caution about financing conditions, not a more precise diagnosis.
Sector rotation: mixed headlines, limited performance data
The event roundup covered a broad range of industries, but it did not provide sector-index returns. It is therefore not possible to identify a confirmed sector leader or laggard from the supplied figures. The headlines do, however, map the issues investors were weighing across the market.
In utilities, the discussion centered on balancing clean-power ambitions with grid requirements. That tension reflects the need to match new sources of electricity with dependable capacity and infrastructure. For utilities and power-related businesses, investment needs, regulation, fuel availability and financing costs can all influence expectations. The supplied information does not indicate whether utility shares rose or fell during the session.
Materials and mining were framed around critical minerals, while energy markets were focused on winter natural-gas risks. Both themes highlight the importance of supply and infrastructure in the outlook for commodities. They do not, on their own, establish the direction of commodity prices or related equities on November 12. Similarly, the industrial and manufacturing roundup referenced AI and CNH, but provided no sector performance figures or additional detail sufficient to assess the broader group’s trading.
Real estate headlines pointed to deals, AI and financing shifts, while financial and banking coverage focused on rates and merger activity. Those themes connect back to the yield backdrop: financing costs can affect property transactions and bank balance sheets, although the impact varies by company and business model. Communications and media were described as sending mixed signals. Consumer and retail coverage highlighted holiday pressures, a reminder that seasonal demand and household spending remain central concerns as the year-end period approaches. Cannabis coverage focused on reform and regulation, suggesting policy uncertainty remained part of the sector’s investment landscape.
Taken together, the headlines describe a market negotiating multiple crosscurrents rather than a clear, data-confirmed rotation into one group. The modest declines in SPY and QQQ, alongside the sharper fall in IWM, provide the clearest measurable evidence of the day’s relative performance.
Company moves: sharp gains amid a lower market
Several company-specific stories stood out against the weaker index backdrop. Cerebras was reported to have surged 13% after a Microsoft deal. The supplied item does not provide details of the agreement, so the move can be described as a strong market response to the announced deal without drawing conclusions about its financial scale or long-term impact.
Intel (INTC) rose 7.46% in the day’s trading, according to the event list. No accompanying catalyst was supplied, so the gain should be treated as a reported price move rather than attributed to a particular product, earnings update or corporate announcement. Archer Aviation was reported up 6% despite a buying-related headline; the precise nature of that item was not specified.
Other corporate developments included Cisco earnings described as a beat, with AI revenue expected to double, and a Box results and revenue-outlook item. The data does not include the companies’ exact reported figures, forward guidance, or stock reactions, so those headlines cannot be ranked by market impact here. The Manitowoc was also cited for Q3 outperformance, while Avicanna was reported to have turned EBITDA-positive after an Ottawa cut. These developments are company-specific and do not establish how their wider sectors traded.
On the downside, the event roundup described a crypto-sector slide following a market shock and reported an EyePoint Q3 loss alongside a setback in wet age-related macular degeneration. No percentage moves or full list of declining tickers were provided for either story. Accordingly, there is not enough information to identify the day’s three largest stock decliners or to quantify the breadth of losses beyond the index ETF figures.
Economic data and Federal Reserve implications
No specific economic release, inflation reading, labor-market report or Federal Reserve announcement was included in the supplied data. That limits the scope for assessing whether the market’s move reflected a change in expectations for near-term policy. The Treasury-yield headline is relevant to that discussion, but a touch of 5% alone does not reveal why yields moved or how traders revised their outlook for Federal Reserve decisions.
For market participants, the distinction matters. A yield increase driven by stronger growth expectations can carry a different message from one driven by inflation concerns, changing Treasury supply expectations or shifts in term premiums. The event list does not identify which factors were in play. The appropriate conclusion is therefore narrow: rates were prominent in the day’s coverage, and the larger decline in small caps is consistent with heightened sensitivity to financing conditions, but the data does not establish a precise Fed-policy narrative.
Looking to the next session
For the next trading session, attention is likely to remain on Treasury yields and whether the small-cap weakness persists or narrows. A continued yield advance could keep financing-sensitive shares in focus; a pullback in yields could change that pressure, though it would not guarantee a rebound. The relationship between IWM and the large-cap ETFs will be a useful measure of whether the day’s relative weakness in smaller companies was a one-session move or part of a broader pattern.
Company news will also matter. The reported reactions to the Cerebras-Microsoft deal and Intel’s gain show that individual catalysts can diverge sharply from the index trend. Follow-through in those names, along with additional details on Cisco, Box and other reported corporate developments, may help determine whether investors are rewarding specific earnings and AI-related stories despite a cautious broader tape.
The next session’s outlook remains conditional rather than directional. The available data does not include a scheduled economic calendar, expected earnings releases or futures indications, so there is no firm basis here for projecting the next close. For now, the November 12 message is a modest decline in large-cap benchmarks, a substantially weaker small-cap ETF, and a market backdrop in which rates, financing and company-specific news remain prominent. This recap is for informational purposes only and is not investment advice.
Sources
+ 10 more sources
Use these insights — enter this week's contest.
Free practice contests — earn Alpha CoinsExplore More Content
Disclaimer: StockAlpha.ai content is for informational and educational purposes only. It is not personalized investment advice. Sentiment ratings and market analysis reflect data-driven observations, not buy, sell, or hold recommendations. Always consult a qualified financial advisor before making investment decisions. Past performance does not guarantee future results.
Spotted something wrong? Report an error.