
 Alpha Breaking
Dream Retirement: $2000000 a Year - Nov 12
Share this article
Spread the word on social media
The Big Picture
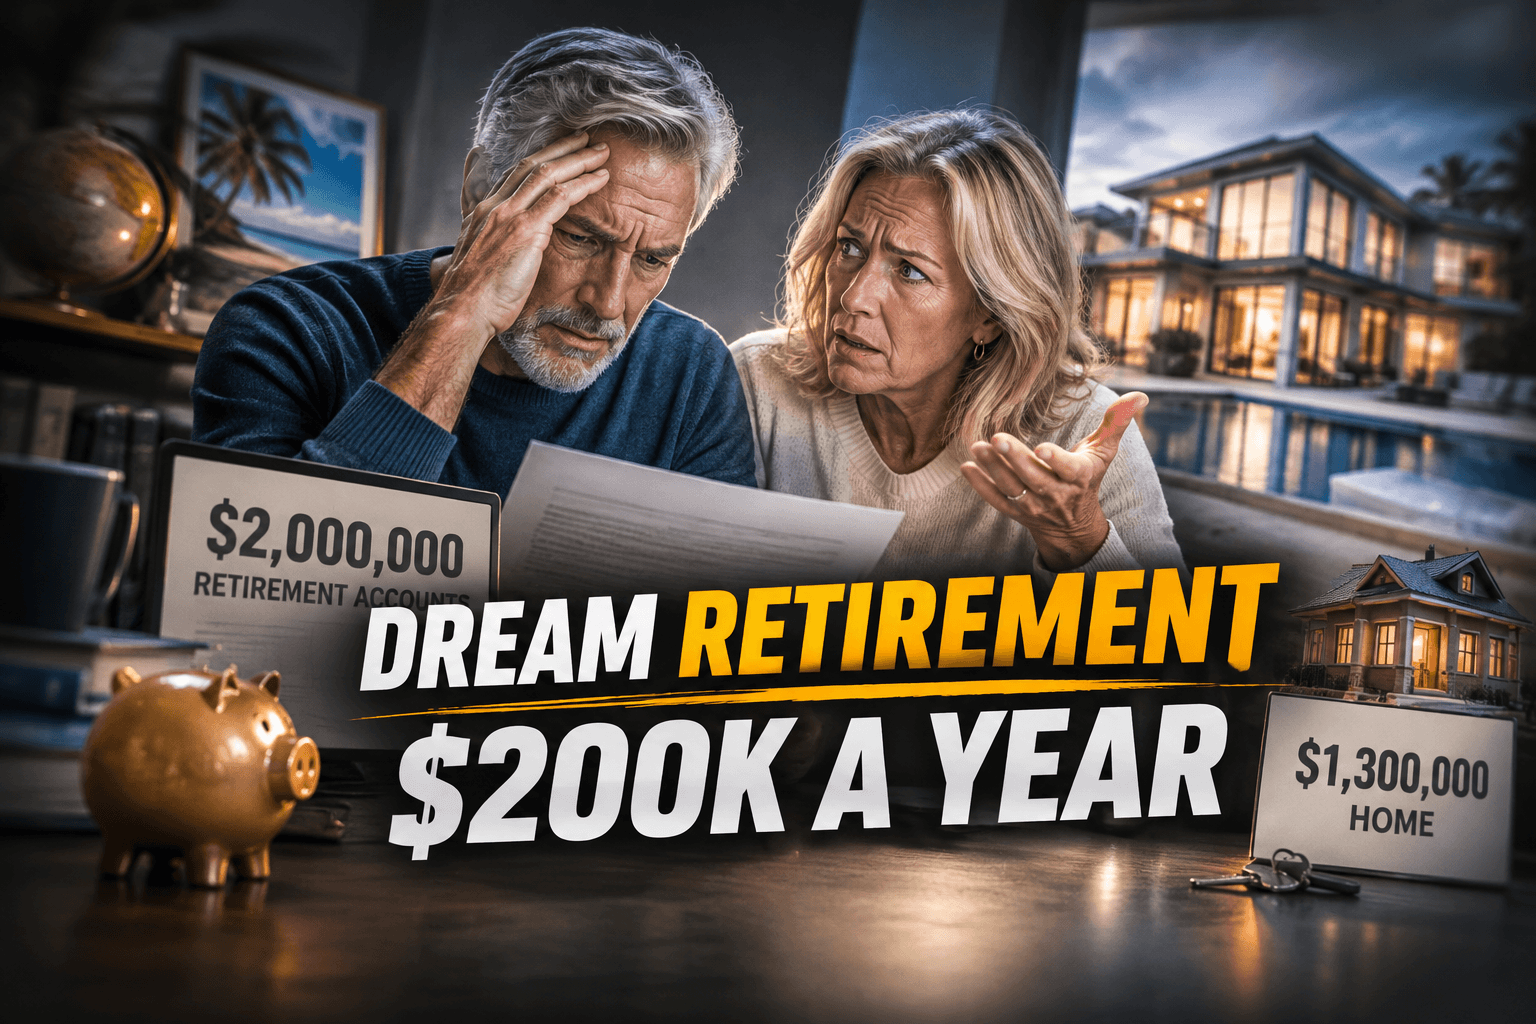
A $200,000-a-year retirement target translates to about $16,667 a month, and the couple’s reported $2 million in retirement accounts would not, by itself, support that spending under a rough 4% initial-withdrawal guideline. That points to a real planning gap to examine, not proof that either spouse is right: the couple’s $1.3 million home may matter to their long-term plan, but its value is not the same as readily available retirement savings.
The figures come from a MarketWatch account of spouses disagreeing about their retirement plans. No stock or ticker is directly involved, and the available information doesn’t include a current market quote. For your own planning, the key takeaway is to test the spending target against income, expenses, and assets that can actually fund it.
What's Happening
The central disagreement is about whether the couple can sustain a desired $200,000 annual retirement budget. That amount is a spending target, not confirmed current income or a completed financial plan. The reported account balances are useful starting points, but they don’t show the couple’s ages, retirement dates, debts, expected benefits, or whether the home will be sold or otherwise used.
- $200,000 a year equals about $16,667 a month, before taxes, healthcare, inflation, or one-time expenses.
- The couple reports $2 million in retirement accounts. A 4% initial withdrawal from that amount would be about $80,000 in the first year, before considering taxes or other income.
- A rough calculation at 4% suggests about $5 million in investable assets to support $200,000 of initial annual withdrawals. It is a rule of thumb, not a guarantee or a personalized plan.
- The home is reported to be worth $1.3 million. That is a property value, not necessarily home equity or cash available for spending, since the source information doesn’t specify any mortgage or plans to sell.
The simple comparison helps explain why the spouses may see the plan differently. If the couple expects to rely only on the $2 million in retirement accounts, the $200,000 target is far above the roughly $80,000 first-year withdrawal produced by the 4% illustration. But Social Security, pension income, work income, a home sale, or lower spending could change the calculation. None of those details is provided, so the $5 million figure shouldn’t be treated as a definitive required balance.
The 4% guideline also doesn’t promise that a portfolio will last indefinitely. The result depends on how long retirement lasts, investment returns, asset allocation, inflation, taxes, and whether the target is expressed in today’s dollars. A spending plan also needs to account for expenses that don’t arrive evenly each year.
Why It Matters For Your Portfolio
This is a household-planning story rather than a company earnings or market event, so there’s no direct effect on a particular stock or sector to assess. For people managing investments for retirement, however, the spending target and withdrawal rate are connected: a high planned withdrawal can make the portfolio more exposed to market declines, especially early in retirement, when withdrawals may continue while investments are down.
Growth-focused investors nearing retirement may want to understand how a downturn could affect planned withdrawals; people prioritizing stability may focus on dependable income sources and essential expenses. The available information doesn’t provide analyst ratings or company-specific valuation data. It does offer several planning figures to compare, including the $200,000 target, $2 million in retirement accounts, the home’s $1.3 million stated value, and the rough $5 million 4% illustration. Those figures can frame a discussion, but they aren’t enough to determine what the household can afford.
Risks To Consider
The main risk is treating a single withdrawal-rate estimate as a guarantee. A detailed cash-flow plan should account for both spouses’ expected retirement dates, income, expenses, and the possibility that real-world costs differ from the target.
- Inflation can erode purchasing power, while market losses early in retirement can make it harder to sustain withdrawals. A longer-than-expected retirement adds more years of spending to fund.
- Taxes, healthcare and long-term-care costs, and large irregular expenses could push the required portfolio above a simple 4% estimate.
- The home’s value may not be available to pay annual bills unless the household has a plan to access that value. The source doesn’t say whether there is a mortgage, a planned sale, or another housing strategy.
In a bearish scenario for the household’s finances, returns disappoint while inflation and healthcare expenses rise, and the couple continues spending near $200,000 a year without enough additional income or assets. That combination could force a change in spending or asset plans. The available facts don’t establish that this scenario will happen, but they make it important to test rather than assume the budget is sustainable.
What To Watch Next
The most useful next step is a detailed retirement cash-flow plan, rather than relying on a general rule or either spouse’s view of what feels affordable. It should include both spouses’ expected retirement dates, assets, income sources, taxes, and spending, with the home treated according to a specific plan rather than simply added to the investment balance.
- Test the plan under lower-return, higher-inflation, and longer-life scenarios to see whether the spending target remains workable.
- Separate essential spending from discretionary spending, then check which costs could be adjusted if investment returns or expenses differ from expectations.
- Clarify how Social Security, pensions, or other income, if applicable, would reduce the amount that must come from investments. The available source information doesn’t specify these income sources.
- Review healthcare, long-term-care, taxes, and irregular expenses alongside the $200,000 annual target, rather than treating it as a simple monthly withdrawal amount.
These planning steps are the relevant catalysts for a clearer answer; the provided information doesn’t identify a scheduled financial event or date. Until the full inputs are assembled, neither the 4% estimate nor the home’s stated value alone settles the disagreement.
The Bottom Line
- The couple reports $2 million in retirement accounts and a home worth $1.3 million, but the available facts don’t establish their complete financial position.
- A $200,000 annual target is about $16,667 monthly, and a rough 4% calculation points to about $5 million in investable assets before taxes and other income.
- The 4% guideline is an illustration, not a guarantee. Retirement length, market returns, inflation, taxes, and healthcare costs can change the outcome.
- A cash-flow plan with essential and discretionary expenses, income sources, and downside scenarios can show what adjustments may be needed.
- This information is for general purposes only, not personalized financial advice or a recommendation to buy, sell, or hold any security.
FAQ
Q: Can $2 million fund $200,000 in annual retirement spending?
A: Under a rough 4% initial-withdrawal illustration, $2 million would generate about $80,000 in first-year withdrawals, not $200,000. Other income, assets, taxes, and spending plans could affect the household’s full calculation.
Q: Does the $1.3 million home close the gap?
A: Not automatically. The reported figure is the home’s value, and the available information doesn’t state its equity, whether the couple plans to sell, or how they might use the property to fund expenses.
Q: Is the 4% guideline a guarantee?
A: No. It is a rule of thumb, and a sustainable withdrawal depends on factors including investment returns, inflation, taxes, asset allocation, and how long retirement lasts.