 Sector Insights
Listen to this Recap
13:36
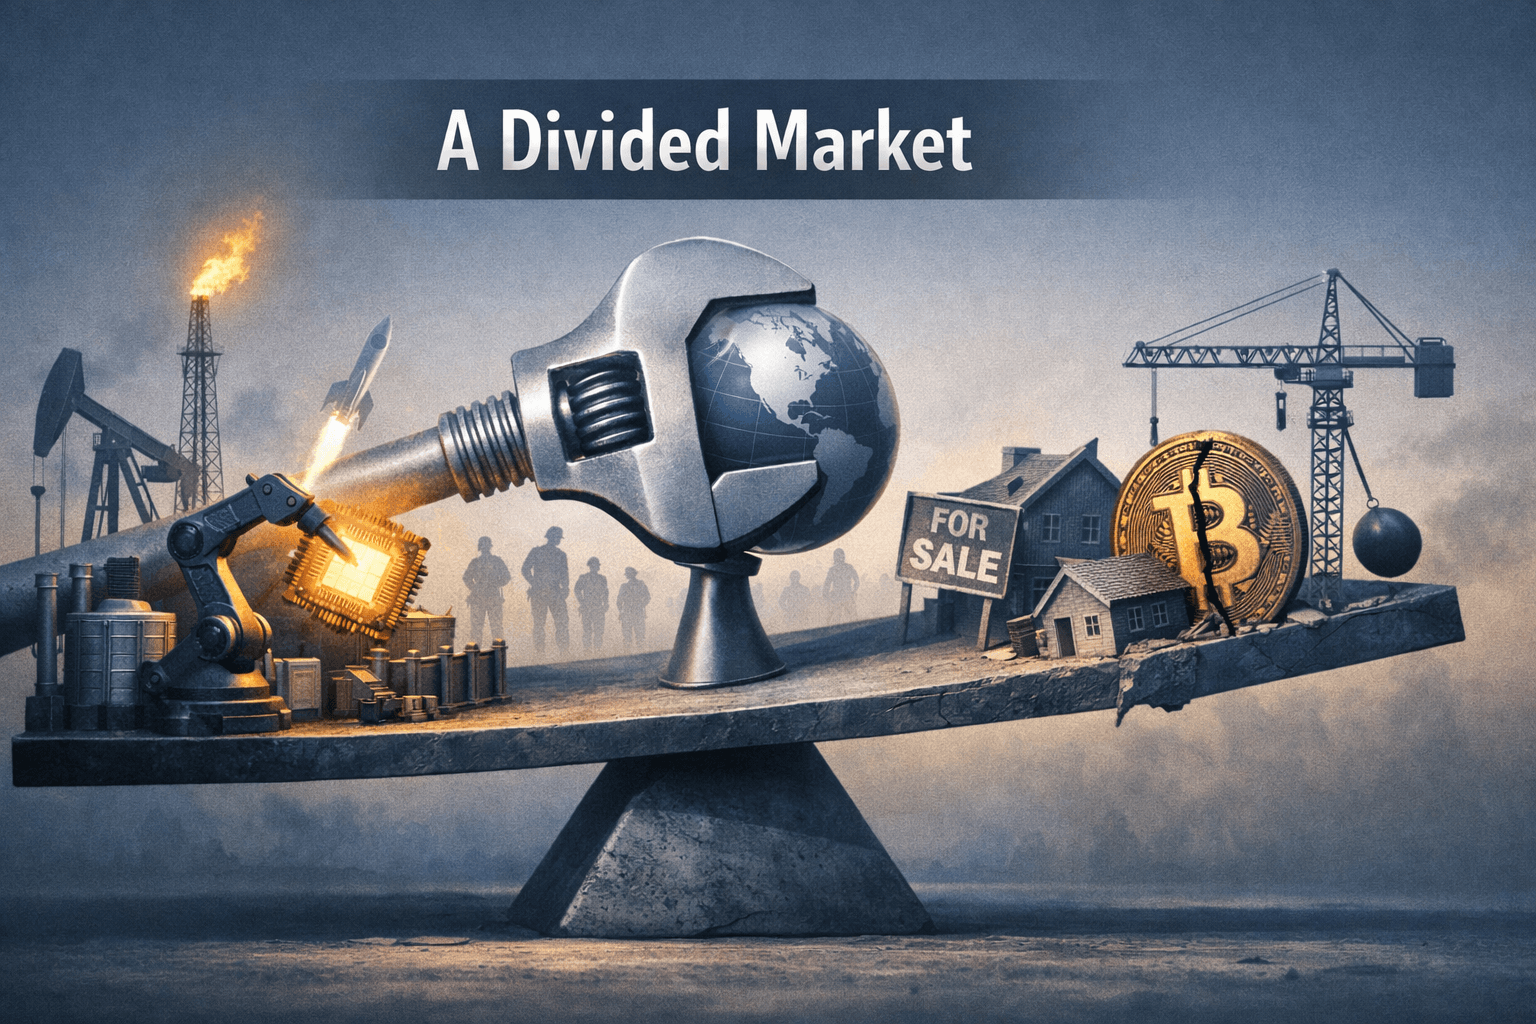
Tightening Rates, Geopolitics and AI Rules Frame a Mixed Market: Energy, Tech and Industrials Lead While Real Estate, Materials and Crypto Languish
Podcast • Loading audio...
Share this article
Spread the word on social media
Key Takeaways
- •Energy and industrials outperformed on geopolitics and capex: Middle East shipping risks and big corporate onshoring plans (e.g., Coca‑Cola’s $10B) drove near‑term momentum.
- •Rate sensitivity keeps real estate under pressure: Near‑7% mortgage rates and cooling rents weigh on property valuations and refinancing risk.
- •AI and regulatory shifts are a key cross‑sector risk: Tech faces legal and compliance variance that will determine winners and losers over multiple quarters.
- •Tokenization offers structural upside for crypto but near‑term macro and regulatory headwinds sustain volatility.
- •Corporate renewables and telecom capex ($92.6B in 2025) provide durable demand themes, but operational and permitting timelines matter for realized returns.
Executive summary
Markets entered the late‑September session confronted by three overlapping forces: a Federal Reserve rate action that keeps borrowing costs elevated; renewed geopolitical friction around Middle Eastern shipping lanes that tightened energy and logistics flows; and a surge of sector‑specific structural stories — AI regulation and litigation in technology, tokenization pathways for crypto, and corporate green procurement deals in energy and utilities.
That mix produced a bifurcated market. Energy, industrials and pockets of technology showed momentum as higher commodity and capex-driven cashflows offset macro uncertainty. Interest‑rate sensitive sectors — notably real estate — and cyclical materials felt the strain of near‑7% mortgage rates and supply‑side shocks. Crypto remained bifurcated between long‑term structural optimism on tokenization and short‑term price pressure driven by macro tightening and regulatory probes.
This recap groups the 24 sectors by performance, parses cross‑sector linkages, highlights the most consequential moves of the day, and offers practical, non‑personalized insights investors can use to referee positioning as the market heads into Q4.
Investment disclaimer: This article presents market analysis and data for informational purposes only. It does not constitute financial advice or a recommendation to buy, sell, or hold any security. Analysts note the themes below as market observations rather than personalized guidance.
Grouping by performance: outperformers, underperformers, stable
Outperformers (momentum/positive catalysts)
- Energy: Geopolitical pressure (Houthi talks, disruptions in the Strait of Hormuz) plus tightening U.S. crude/gasoline balances pushed near‑term pricing power and refining margins higher. LNG prices also rose, tightening fundamentals for the sector.
- Industrials & Manufacturing: Large onshoring announcements and capex plans — Coca‑Cola’s $10B U.S. manufacturing initiative and fresh government support for MEP centers — helped sentiment around capacity and productivity names.
- Technology (select areas): Despite an overarching legal storm around AI training, pockets of strength emerged from enterprise AR and AI product monetization (e.g., Snap’s AR push, Snap Inc.) and sector investment in AI tooling.
Underperformers (rate‑sensitive, shocked by headlines)
- Real Estate: Continued evidence of a sluggish housing market — near‑7% mortgage rates and a frozen four‑year housing market — combined with cooling apartment rents undermined sentiment for property names, especially those with leverage or near‑term refinancing needs.
- Materials & Mining: A fatal mine collapse in Sudan weighed on sentiment, amplifying supply‑risk narratives; steel‑sector uncertainty and mixed financing headlines produced investor caution.
- Cryptocurrency: Macro tightening and high‑profile regulatory moves (South Korea gambling probe, slower institutional BTC buys) pressured crypto prices despite tokenization and ETF optimism.
Stable / Mixed (balanced catalysts)
- Consumer & Retail: Strong M&A and AI integrations (Nike board changes, Ingredion deal, Costco delivery expansion) offset weak grocery volumes and the headline risk of a $73B GLP‑1 impact on snack categories.
- Utilities: Renewables and corporate PPAs (144‑MW PPA tied to META) drove long‑term growth impressions even as grid reliability and winter preparedness remained a near‑term concern.
- Finance & Banking: The sector absorbed the Fed’s rate action with selective analyst optimism; regulatory (AI guidance) and geopolitical flow shifts create idiosyncratic winners and losers.
Cross‑sector themes and correlations
- Fed policy compresses the time window for rate‑sensitive recoveries
- Near‑7% mortgage rates and ongoing Fed tightening keep pressure on REITs, homebuilders, and mortgage lenders. Data suggests that leasing momentum and rental trends are now a bigger determinant of property valuations than headline GDP growth. The finance sector’s internal rotation toward duration‑short instruments and fee income is a parallel reaction. In short: higher rates amplify downside in highly leveraged balance sheets, and increase the premium investors demand for long‑dated cash flows.
- Geopolitics is re‑pricing energy and logistics risk
- Talks with the Houthis and disruptions in the Strait of Hormuz tightened crude and refined product flows today, and Goldman‑linked analysis showed refiners pivoting to diesel is tightening gasoline markets. The immediate impact shows up in energy company near‑term free cash flow and in logistics — shipping costs and insurance spikes — which in turn feed industrials, materials, and real estate (port/logistics real estate) valuations.
- Corporate capex and onshoring as a counterbalance to macro risk
- Large industrial initiatives — Coca‑Cola’s $10B plan, NIST grants to MEP centers, and a $2.4B logistics JV — indicate companies are accelerating investments to secure supply chains and reduce offshore risk. That capex narrative supports industrial machinery, logistics REITs focused on big distribution hubs, and materials demand for construction and manufacturing over the medium term.
- AI regulation and litigation is a new structural risk for tech
- Explosive court filings on AI model training and escalating calls for stringent AI safeguards add legal and compliance risk to the sector. Short‑term, this increases headline volatility for platform and infrastructure names; medium‑term, it may increase compliance costs but also favor firms with clearer data licensing and model governance.
- Energy transition remains active but with operational constraints
- Corporate renewables procurement (e.g., the 144‑MW PPA tied to META) and advances in solar manufacturing (SEG Solar’s 4‑GW HJT initiative) showcase scaling. Still, grid reliability concerns and winter preparedness introduce timing risk for realized emissions reductions and intermittency mitigation.
- Regulatory progress and M&A shape cannabis and pharma narratives
- SAFE Banking back in the Senate and a 45% premium takeover bid by Curaleaf for Aurora are re‑shaping capital access and consolidation expectations in cannabis. In healthcare, Roche’s up‑to‑$1B bispecific pact and a $1.4B pharma tie‑up show deal activity remains a key growth channel.
Most significant moves and context
Curaleaf’s 45% premium bid for Aurora (cannabis)
- Why it matters: A large premium offer for Aurora accelerates M&A expectations in an industry starved for scale and financing. With SAFE Banking back before the Senate, capital access could improve, making consolidation easier.
- Market implication: The move compresses takeover valuations across North American cannabis names and increases takeover chatter for smaller, cash‑constrained operators. Analysts note a successful bid would reset deal multiples and affect bank risk models for the sector.
Coca‑Cola unveils a $10B U.S. manufacturing plan (industrials)
- Why it matters: A concentrated onshoring and capacity upgrade plan by a global brand signals a shift in corporate capex priorities toward resilience and localized production.
- Market implication: This benefits industrial equipment makers, regional logistics networks, and domestic materials suppliers. It also sets a corporate precedent for other consumer staples firms reacting to supply‑chain risks.
$2.4B logistics joint venture and industrial leasing momentum (real estate/industrial)
- Why it matters: Large JV and leasing volumes point to enduring demand for logistics real estate despite mortgage and housing pain. The bifurcation between industrial and residential real estate deepened today.
- Market implication: Investors should monitor rent and vacancy spreads between industrial corridors (outperformance) and residential/apartment sectors (continued pressure).
META‑linked 144‑MW PPA and SEG Solar 4‑GW HJT ramp (utilities/energy transition)
- Why it matters: Corporate PPAs demonstrate that big tech remains a primary driver of renewable demand; at the same time, industrial‑scale PV manufacturing (SEG Solar) closes a portion of the supply chain.
- Market implication: Renewable project developers and inverter manufacturers could see accelerating order books, but grid reliability and permitting remain gating items.
Broadband capex top‑line: $92.6B in 2025 (communications)
- Why it matters: Elevated telecom capex underpins long‑run demand for network equipment and capital goods while highlighting the structural nature of connectivity spending.
- Market implication: Telecom equipment and tower companies stand to benefit from sustained spending, but telecom operators may face margin pressure as they deploy capital.
Healthcare and pharma deals: Roche up‑to‑$1B bispecifics pact; $1.4B pharma tie‑up
- Why it matters: Big biopharma deals show M&A and collaboration remain central to pipeline monetization; the Roche pact is an example of targeted, high‑value R&D partnerships.
- Market implication: Biotech firms with late‑stage assets can expect continued interest from strategic acquirers, even as FDA resourcing and hiring delays add timing risk to approvals.
Crypto tokenization and regulatory dynamics
- Why it matters: The CFTC and SEC signals on tokenized U.S. stocks, plus partnerships around tokenization, could alter the capital market plumbing and spur product innovation (tokenized ETFs, custody solutions).
- Market implication: Tokenization may lower frictions for market participation over time, but near‑term macro tightening and localized regulatory probes (e.g., South Korea) keep price volatility elevated.
Materials and mining: Sudan mine collapse and financing moves
- Why it matters: A fatal mine collapse in Sudan underscores geopolitical and operational risk in raw materials supply, while First Phosphate’s US$212.5m Swiss support shows investors are still funding critical minerals projects.
- Market implication: Supply shocks can produce episodic price spikes and may accelerate recycling and secondary‑supply investments.
Consumer headlines: AI push, private‑label and GLP‑1 risk
- Why it matters: AI integrations (Pinterest, Macy’s forecasting) and delivery expansions (Costco via Uber Eats) show retailers adapting to new workflows and formats. However, a reported $73B GLP‑1 exposure risk to snacks highlights durable changes to food consumption patterns.
- Market implication: Margins and category volumes may re‑rate over time as private‑label penetration and product mix shifts offset or accentuate category declines.
Actionable insights (for informational use only)
Recalibrate duration exposure: With mortgage rates near 7% and an active Fed, analysts suggest reviewing duration risk across portfolios. Data suggests long‑dated cash flows remain vulnerable to further policy tightening; consider monitoring corporate balance‑sheet strength and refinancing windows.
Watch capex beneficiaries: The $10B Coca‑Cola plan, $2.4B logistics JV, and sustained broadband capex ($92.6B in 2025) point to a set of beneficiaries across industrial machinery, logistics REITs, telecom equipment, and materials. Investors tracking earnings beats and order‑book upgrades in these subsegments can separate durable winners from headline‑driven rallies.
Hedge geopolitical exposure: Short‑term energy and shipping disruptions can produce fast, asymmetric moves. Hedging strategies around energy re‑pricing, or monitoring freight rate and insurance cost signals, are prudent for portfolios with logistics sensitivity.
Monitor AI legal outcomes: The legal environment around AI training and data licensing is a multi‑quarter catalyst. Firms that disclose clearer licensing, model governance, or enterprise AI revenue may outperform peers facing opaque litigation risk.
Distinguish renewable procurement from operational delivery: Corporate PPAs and new manufacturing lines are positive, but grid reliability and permitting can delay realized benefits. Track project COD (commercial operation date) schedules and interconnection queues for realistic timing of revenue and carbon impacts.
Read cannabis and banking policy headlines closely: SAFE Banking activity in the Senate and M&A bids (e.g., Curaleaf/Aurora) can materially change cash access for cannabis operators. Policy roll‑through could alter liquidity profiles and valuation multiples.
Separate tokenization hype from near‑term execution: Tokenized stocks and ETFs could be transformative but require custody, regulatory clarity, and market‑making infrastructure. Data suggests pilot programs and early ETFs will be informative for actual adoption curves.
Risks and watchlist (what could change the narrative)
- A surprise move in Fed policy or a materially stronger CPI/PCE print could push rates higher and re‑accelerate stress in real estate and rate‑sensitive credit markets.
- Escalation in Middle East maritime risk or a new supply‑side shock (Russian fuel flows, Sudan operational disruption) could materially widen energy volatility and insurance costs.
- Adverse legal rulings or regulatory fines in the AI space could create outsized headline risk for large platform names and their suppliers.
- Legislative outcomes on SAFE Banking and other sector‑specific bills (telecom, energy incentives) could rapidly re‑price capital access and investment incentives.
Conclusion: looking ahead to Q4
The market’s current posture is one of guarded adaptation: companies are accelerating capex and reshaping supply chains while investors price an elevated premium for certainty around earnings and cash flows. Energy and industrials are the short‑term beneficiaries of tighter commodity and logistics dynamics, whereas real estate and materials face a more uncertain path as higher rates and on‑the‑ground risks play out.
In the coming weeks, three levers will determine the market’s direction: the Fed’s next communications and data prints, the trajectory of Middle East shipping risks, and the evolution of AI regulatory outcomes. Corporate earnings that show durable pricing power or demonstrable margin improvement from capex deployments will likely attract capital; conversely, sectors with heavy refinancing needs or exposure to volatile commodity inputs will remain sensitive to macro headlines.
Analysts note the present environment rewards selectivity and vigilance: track balance‑sheet health, near‑term cash flows, and the timelines for project execution (PPAs, manufacturing ramps, and regulatory approvals). For investors watching sector rotation, the signals today favor energy and industrials for momentum, with technology a source of both growth and headline risk, while real estate, materials and crypto require closer risk‑management attention.
Key data points cited in this recap: Curaleaf’s 45% premium bid for Aurora; Coca‑Cola’s $10B U.S. manufacturing plan; a $2.4B logistics joint venture; a 144‑MW PPA tied to META; SEG Solar’s 4‑GW HJT output start; broadband capex of $92.6B in 2025; First Phosphate’s US$212.5m Swiss support; a $1.4B pharma tie‑up; Roche’s up‑to‑$1B bispecifics pact; and near‑7% mortgage rates.
This synthesis is intended to help market participants prioritize the right signals as Q4 earnings season and policy calendars converge. As always, data suggests that staying disciplined around liquidity, duration, and regulatory exposures will be central to navigating the volatility ahead.
Investment reminder: This article is informational and does not constitute personalized investment advice. Analysts’ views expressed here are market observations and should not be treated as individual recommendations.
Sources
+ 14 more sources
Use these insights — enter this week's contest.
Free practice contests — earn Alpha CoinsExplore More Content
Disclaimer: StockAlpha.ai content is for informational and educational purposes only. It is not personalized investment advice. Sentiment ratings and market analysis reflect data-driven observations, not buy, sell, or hold recommendations. Always consult a qualified financial advisor before making investment decisions. Past performance does not guarantee future results.