 Breaking Analysis
Listen to this Recap
9:36
Rates Shock and Idiosyncratic Catalysts: Bonds Under Pressure, AI and Cloud Drive Select Equity Stories
Podcast • Loading audio...
Share this article
Spread the word on social media
Key Takeaways
- •Long-term yields surged: 30-year Treasury hit 5.401%, re-pricing duration and increasing dispersion across assets.
- •Cash and short-duration alternatives now offer nominal yields around 5.1%–5.113%, but tradeoffs in liquidity, credit and inflation protection remain.
- •Company-specific catalysts (Meta/Google AI launches, Oracle cloud momentum, Intuitive Surgical trade-ins, Micron customer/pricing signals) are driving cross-sectional opportunities and risks.
- •Rising benchmark rates are filtering into consumer credit (auto loan APRs) and pressuring affordability, with implications for OEMs and finance units.
- •Analysts agree on the macro re-pricing but disagree on timing/magnitude of equity monetization from AI and the durability of company-level catalysts.
The day's most significant development
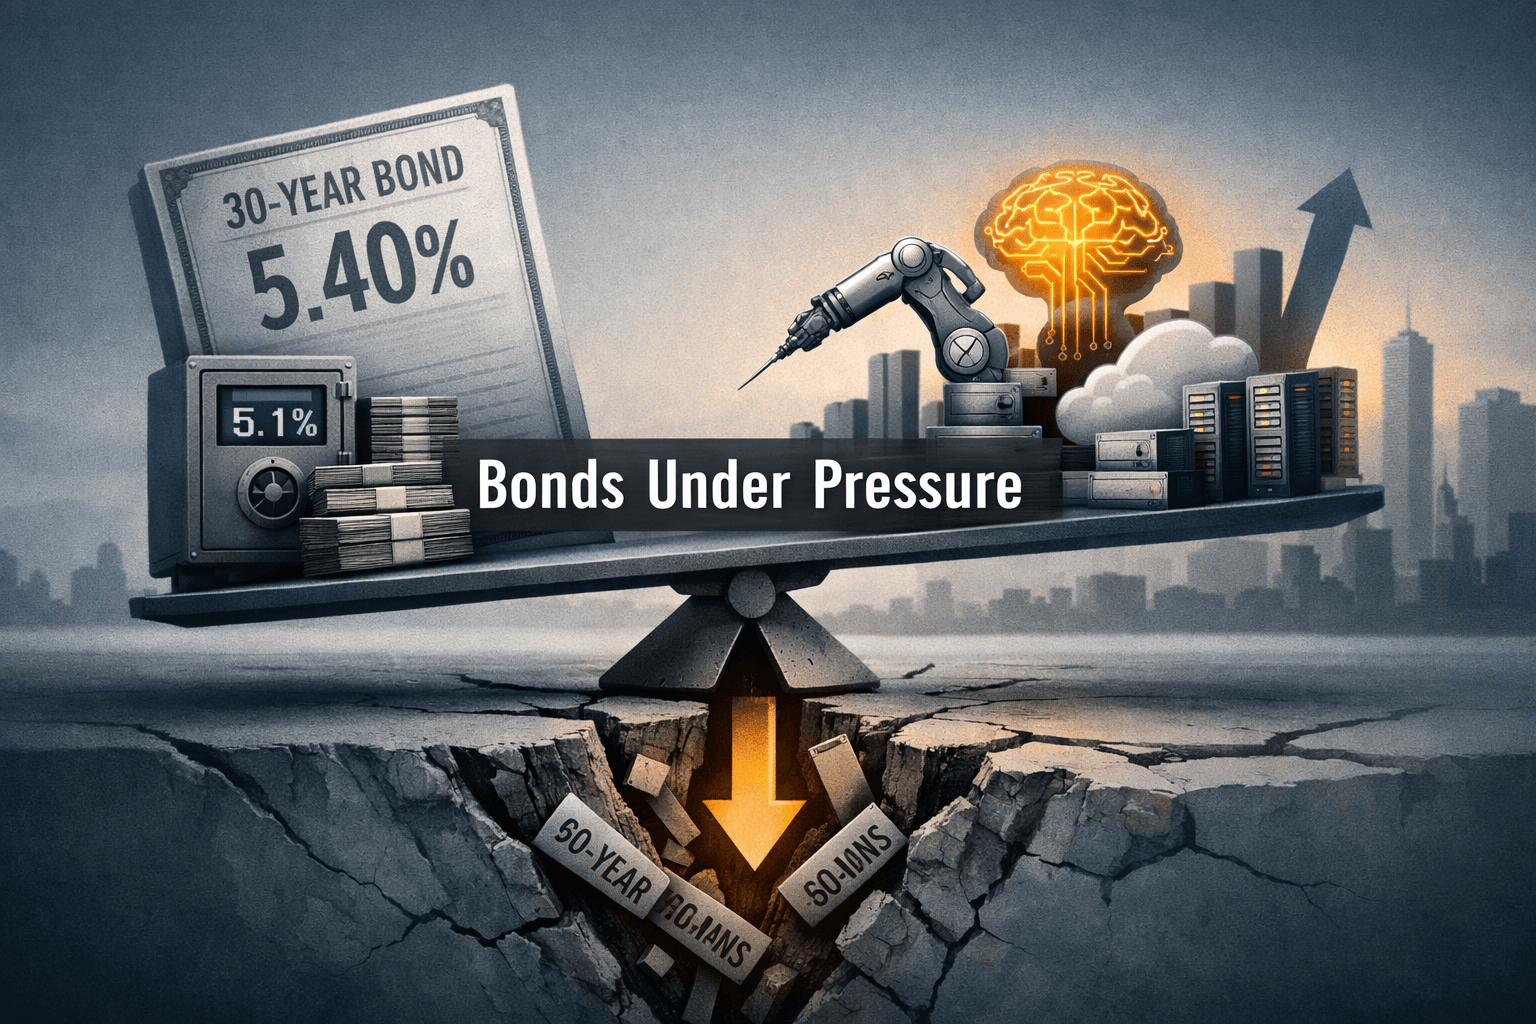
The bond market ripple from Wednesday dominated market analysis: the 30-year Treasury yield climbed to 5.401% — the highest level since 2004 — with the 10-year sitting around 5% in several reports. Analysts and market commentary framed this as a structural recalibration of duration risk and the return opportunity from cash and short-duration instruments. That move is feeding through to consumer finance (auto loan APRs), equity valuations for long-duration growth names, and a renewed search for income alternatives that can match or exceed what long-term Treasuries once offered.
Cross-cutting themes across today's coverage
- Rising long-term rates reshape the income trade
- Multiple pieces flagged a multi-year bond slump and the practical effect of higher benchmark yields. The 30-year at 5.401% and the 10-year near 5% are pushing investors to question traditional fixed-income allocations. Analysts cite that cash-like and short-duration products are now offering yields in the neighborhood of 5.1%–5.113%, creating a straight comparison between near-term, low-duration yields and the price volatility of longer-maturity bonds.
- The coverage of “Here Are 3 Alternatives for Investors” summarized the central trade-off: alternatives (cash-like vehicles, short-duration instruments, yield-focused equities) can deliver competitive nominal yields but each has distinct tradeoffs in liquidity, credit risk and upside participation.
- Macro force meets micro catalysts — dispersion rises
- Rising yields are exerting downward pressure on duration-sensitive sectors, but corporate-specific news is creating pockets of opportunity and risk. JPMorgan’s price-target lift for Meta after the Muse showcase and Google’s Gemini 3.8 Live launch point to renewed optimism around AI monetization. Oracle Japan’s Q1 transcript shows double-digit cloud and subscription growth, suggesting cloud revenue momentum persists at some incumbents.
- At the same time, company-specific flow metrics matter: Intuitive Surgical logged 144 da Vinci 5 trade-ins in fiscal Q2 (up from 83 a year earlier), a concrete signal analysts say could lift procedure revenue and per-surgery economics. Micron faces a critical week in which Rosenblatt and others are focused on customer agreements, rising memory prices and buybacks as binary catalysts for the stock.
- Consumer and credit channels feel the rate squeeze
- Reports on auto-finance costs emphasized a clear transmission mechanism: higher Treasury yields are swift upstream drivers of auto loan APRs, which in turn pressure demand, captive finance units and used-car prices. Analysts warned that a higher-rate environment reduces affordability for big-ticket items and can slow sales across OEMs and dealerships.
- Consumer staples moves (PepsiCo planning price hikes; Procter & Gamble’s muted post-Q2 path) showed companies are acting to defend margins, but execution and consumer tolerance are open variables.
Where analysts broadly agree — and where they diverge
Agreements
- Rising long-term yields materially change the risk/reward calculation for fixed-income and long-duration equities. The 30-year at 5.401% is not a marginal headline — analysts say it re-prices duration.
- Alternatives exist for income seekers: cash and short-duration vehicles yielding ~5.1% are attractive on a nominal-yield basis, but have different liquidity and inflation-protection profiles versus bonds.
- Corporate-specific catalysts (AI product rollouts, cloud growth, surgical-robot upgrades, memory-cycle indicators) will drive cross-sectional dispersion in equity performance.
Divergences
- AI and product-monetization timelines: JPMorgan’s upgrade of Meta (with an $820 target) and the market attention to Google’s Gemini 3.8 Live reflect bullish assumptions about near- to medium-term monetization of new AI features. Other analysts temper that enthusiasm, pointing to long monetization lags, ad-revenue cyclicality and implementation risk.
- The valuation appetite for beaten-down names: some analysts view Intuitive Surgical’s trade-in momentum and Micron’s potential buyback/price-improvement signals as reason for constructive reappraisal; others stress that macro headwinds and competitive pressures keep conviction sideways until management confirms durable trends.
- Streaming vs. growth: Netflix reports double-digit 2026 revenue growth yet faces skepticism about sustainable margins and competition — Zacks’ profile highlights the tension between top-line strength and market skepticism.
Deeper context on major moves
Why the 30-year matters beyond a rate quote
- The 30-year yield anchors mortgage costs, pension liabilities and long-term corporate discount rates. When it jumps to the multi-percent range not seen since 2004, it alters the present-value math for future cash flows: growth stocks, whose valuations rely on cash flows far into the future, face multiple compression. Conversely, short-term cash vehicles and near-term revenue models look relatively more attractive.
Income alternatives: the nuance behind the headline yields
- A recurring data point in the “alternatives” pieces was yields ~5.1% (and a more precise 5.113% in one model). Those figures are enticing on the surface, but analysts remind readers to consider liquidity, credit risk and tax treatment. For example, a high-yielding shorter-term corporate product may match the headline yield but carry credit spread and event risk absent in Treasuries.
AI product demonstrations vs. monetization risk
- Meta’s Muse and Google’s Gemini 3.8 Live are examples of product-driven optimism. Analysts note that product demos can shift narrative and analyst assumptions — JPMorgan raised Meta’s target on Muse’s perceived potential — but translating that into consistent, material revenue (and earnings) requires time, enterprise adoption and scalable pricing. The market’s near-term reaction reflects a re-pricing of optionality rather than an immediate fundamental re-rating in most coverage.
Auto finance transmission
- Analysts emphasized an often-underappreciated chain: Treasury yields → prime and benchmark curves → vehicle financing spreads → consumer monthly payments → sales and used-car price dynamics. The practical takeaway is that higher benchmark yields quickly tighten affordability corridors for buyers, which can show up in OEM sales, captive finance results and subprime credit metrics.
Implications for different investor types
Income-oriented investors (retirees, income allocators)
- Data suggests nominal yields on cash and short-duration options are compelling (~5.1%). Analysts note these vehicles reduce duration risk relative to long-term bonds but may require tradeoffs in inflation protection and long-term real return. Investors focused on stability will weigh duration reduction and liquidity as priorities.
Growth-biased investors (tech/AI exposure)
- Product-led optimism (Muse, Gemini 3.8 Live, Oracle’s cloud momentum) supports selective reappraisal of growth names. However, rising long-term rates increase discount-rate sensitivity. Analysts caution that exposure should reflect conviction in monetization timelines and tolerance for headline-driven volatility.
Value/trading investors (event-driven, cyclical)
- Company-specific catalysts (Micron’s expected customer agreements/pricing moves, Intuitive’s upgrade cadence) create tradable events. Market commentary suggests heightened dispersion — good for active stock pickers — but also warns binary risk if management commentary disappoints.
Conservative/portfolio managers (fixed income allocation managers)
- The yield environment warrants reassessing duration buckets and exploring cash-like or short-duration sleeves. Analysts stress the importance of modeling reinvestment assumptions and the potential for further Fed action; liability-driven mandates may need re-pricing.
Consumer and credit-focused investors
- Higher auto financing costs and consumer price actions (PepsiCo hikes) signal pressure points across discretionary demand. Analysts flag scrutiny of captive finance results, used-car price trends and consumer staples volume elasticity as important monitoring areas.
Strategic considerations and next steps that analysts highlight
- Reassess duration exposure: rising long-term yields call for explicit stress-testing of bond sleeves under higher-rate scenarios and laddering to manage reinvestment risk.
- Treat AI/product stories as narrative catalysts with execution risk: monitor monetization metrics, enterprise sales cadence and ad-revenue sensitivity instead of extrapolating demo-level enthusiasm into near-term earnings certainty.
- Use dispersion to your advantage: higher yields and macro uncertainty typically increase cross-sectional stock moves. Analysts suggest tighter position sizing and focused event risk management around name-specific catalysts (Micron earnings, Intuitive upgrade trends, Oracle cloud guidance, Netflix competitive positioning).
- For income seekers, run a tradeoff analysis: nominal yields around 5.1% for cash/short-duration products look attractive, but you should model tax, liquidity, and inflation impacts compared with a diversified income approach.
- Monitor macro checkpoints: Treasury auction results, Fed commentary, and inflation data remain the control variables that will determine whether yields stabilize or climb further.
Conclusion
Today's tape is a reminder that macro and micro forces now coexist in a way that increases portfolio dispersion. The surge in long-term Treasury yields (30-year at 5.401%; 10-year near 5%) re-prices duration and strengthens the case for low-duration income alternatives that can deliver yields in the low-5% range. At the same time, company-level catalysts — from AI product launches and cloud acceleration to surgical-robot trade-in momentum and semiconductor cycle signals — are generating idiosyncratic opportunities and risks. Analysts broadly agree on the macro backdrop but diverge on how quickly product optionality will convert to durable cash flow. For investors, the imperative is to match exposure to time horizons, liquidity needs and conviction in execution: run scenario analyses, prioritize risk management around event-driven names, and keep macro checkpoints — Fed actions, inflation prints, and Treasury demand — at the center of allocation conversations.
Investment disclaimer: This synthesis presents analysis and data for informational purposes only. It does not constitute a recommendation to buy, sell or hold any security, nor does it provide personalized investment advice. Analysts note trends and metrics; readers should consult their financial advisors before making portfolio decisions.
Sources
+ 7 more sources
Use these insights — enter this week's contest.
Free practice contests — earn Alpha CoinsExplore More Content
Disclaimer: StockAlpha.ai content is for informational and educational purposes only. It is not personalized investment advice. Sentiment ratings and market analysis reflect data-driven observations, not buy, sell, or hold recommendations. Always consult a qualified financial advisor before making investment decisions. Past performance does not guarantee future results.